


US Employment Situation: January 2026
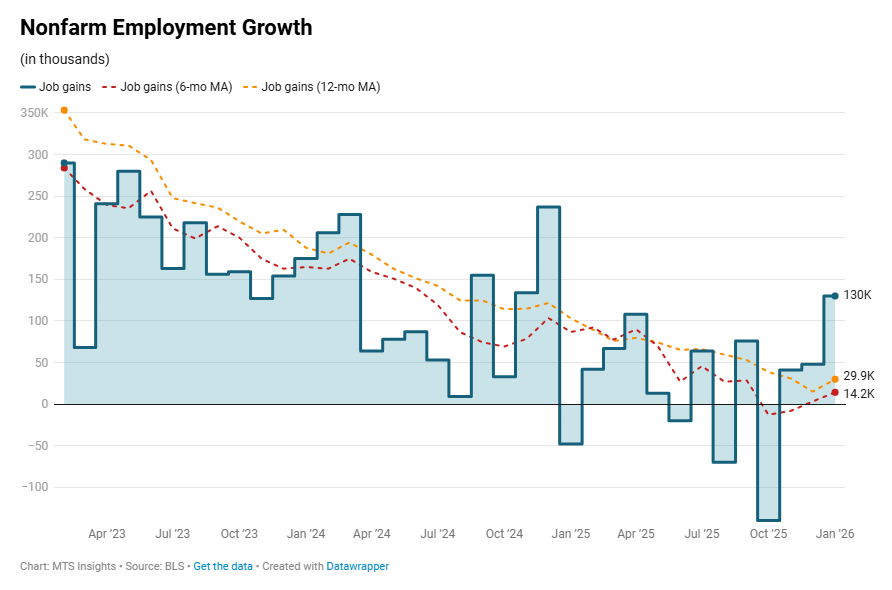
U.S. nonfarm payrolls rose +130,000 in January (vs 70,000 expected) while the unemployment rate fell -0.1 ppt to 4.3%, signaling renewed labor market stability at the start of 2026.
-
Nonfarm payrolls increased +130,000 in January, the strongest gain since April 2025, lifting the 3-month average to +73,000 after negative prints in November (-8,000) and December (-17,000), indicating a rebound in hiring momentum.
-
Private payrolls rose +172,000, offsetting a -42,000 decline in government employment; federal payrolls fell -34,000 and are now down -327,000 (-10.9%) from their October 2024 peak, showing continued public-sector drag.
-
Within private hiring, goods-producing jobs increased +36,000, led by construction (+33,000), while manufacturing added +5,000 after prior weakness; services added +136,000, with health care and social assistance contributing +123,500, underscoring concentration in one sector.
-
Annual benchmark revisions lowered March 2025 payroll levels by -898,000 SA, cutting 2025 job growth from +584,000 to +181,000, marking the weakest year since 2003 and indicating prior labor strength was overstated.
-
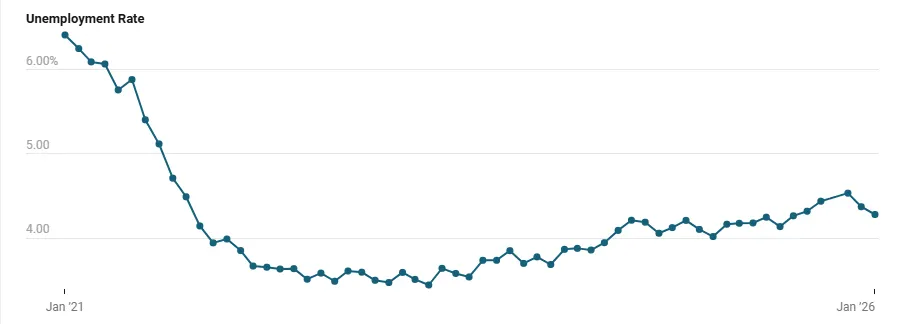
The unemployment rate declined to 4.3% (-0.1 ppt MoM; -0.26 ppts since November but +0.26 ppts YoY), as employment rose +528,000 and the labor force increased +387,000; both participation (62.5%) and the employment-population ratio (59.8%) rose +0.1 ppts.
-
The number of unemployed fell -141,000, long-term unemployment declined -113,000, and part-time for economic reasons dropped -453,000, pointing to improvement in broader underemployment measures.
-
Prime-age (25–54) unemployment held at 3.7% (0.0 ppts MoM), while the 25–34 cohort rose +0.5 ppts to 4.8%, and youth unemployment (16–19) fell -1.9 ppts MoM to 13.6% but remains about +2 ppts YoY, highlighting mixed age dynamics.
-
Average hourly earnings rose +0.4% MoM and +3.7% YoY (unchanged YoY), with goods wage growth easing to +4.0% YoY (from +4.2%) and services near +3.65% YoY, maintaining wage growth within the 3.5%–4.0% range.