

Investment Manager Index: February 2026
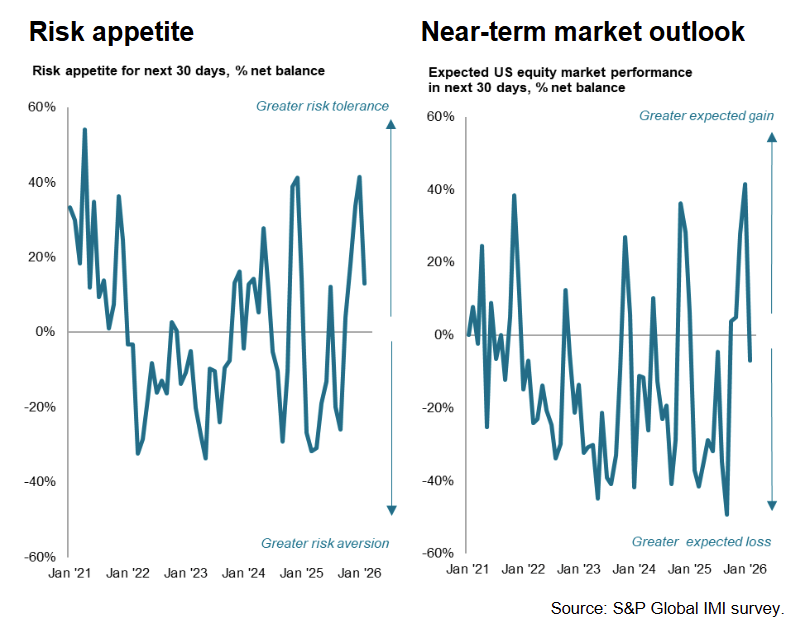
The S&P Global IMI Risk Appetite Index fell to +13% in February 2026 (from +41% in January), signaling a sharp pullback in near-term equity optimism despite remaining positive.
-
Risk appetite declined sharply from January’s 13-month high, reaching its lowest level since October, though staying in positive territory for a fifth consecutive month.
-
Expectations for U.S. equity returns over the coming month turned negative for the first time since September, reversing the survey-high optimism seen at the start of the year.
-
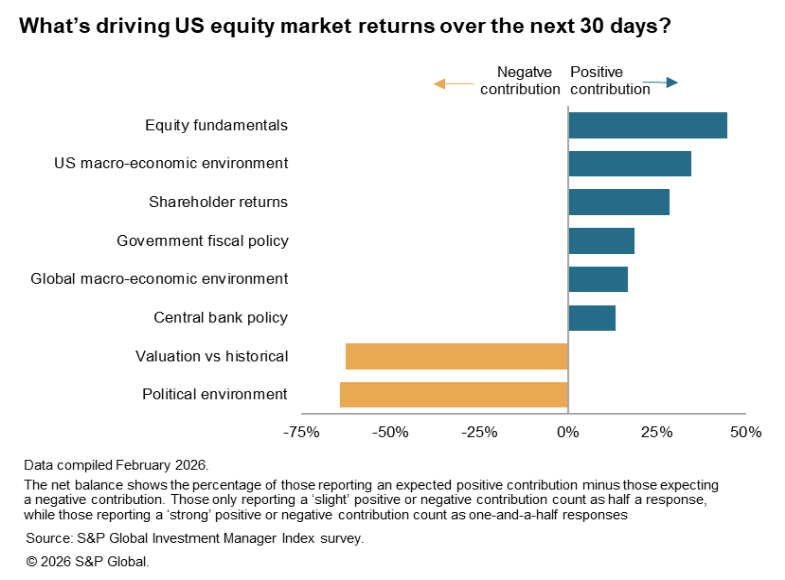
Political concerns intensified, with worries about their impact on equities rising to joint-highest levels since June and surpassing valuation concerns as the largest drag on sentiment.
-
Expectations for central bank policy support weakened further, falling to their least optimistic level since August as investors anticipated fewer imminent rate cuts.
-
Fiscal policy and the global macro environment remained net positives for U.S. equities, but their perceived support cooled from the elevated levels recorded in January.
-
In contrast, equity fundamentals became the strongest positive driver for the first time since July, with optimism around earnings rising to a four-year high.
-
Sector preferences shifted toward industrials, energy, and basic materials, while investor favor fell for financials and technology; real estate and consumer discretionary remained the least favored sectors.