

Investment Manager Index: January 2026
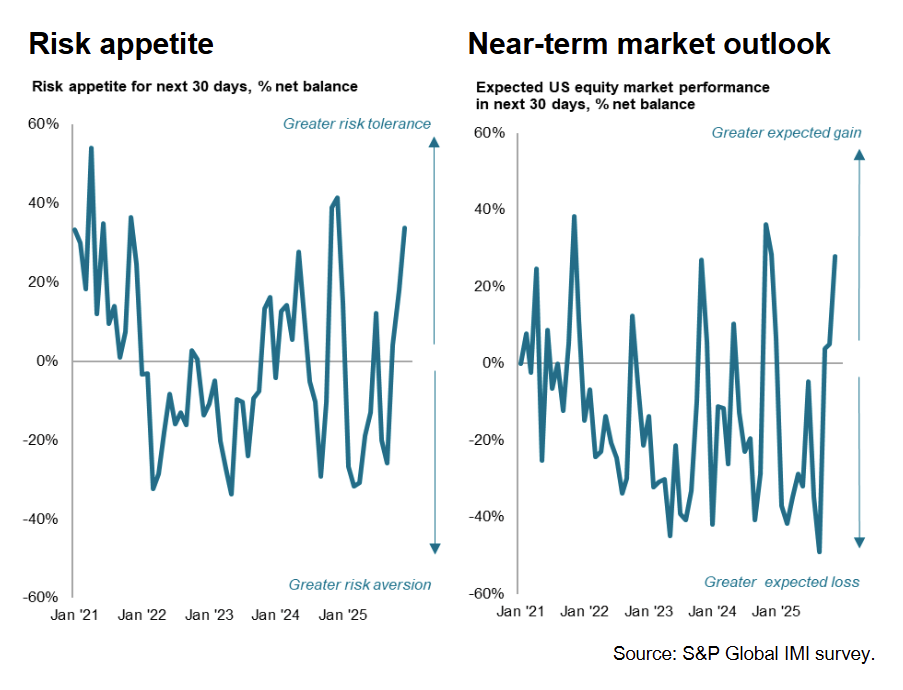
The S&P Global IMI Risk Appetite Index rose to +41% in January 2026 (from +34% in December), reaching a joint-high since April 2021 and signaling a stronger “risk-on” tone tied to improving market expectations for 2026.
-
The Risk Appetite Index has now increased for four consecutive months, reaching its strongest level since April 2021, consistent with a broad rebound in investor sentiment entering 2026.
-
Near-term expectations for U.S. equities strengthened further, with 58% of respondents expecting gains over the coming month versus 16% expecting declines, marking the most optimistic one-month return outlook since the survey began in October 2020.
-
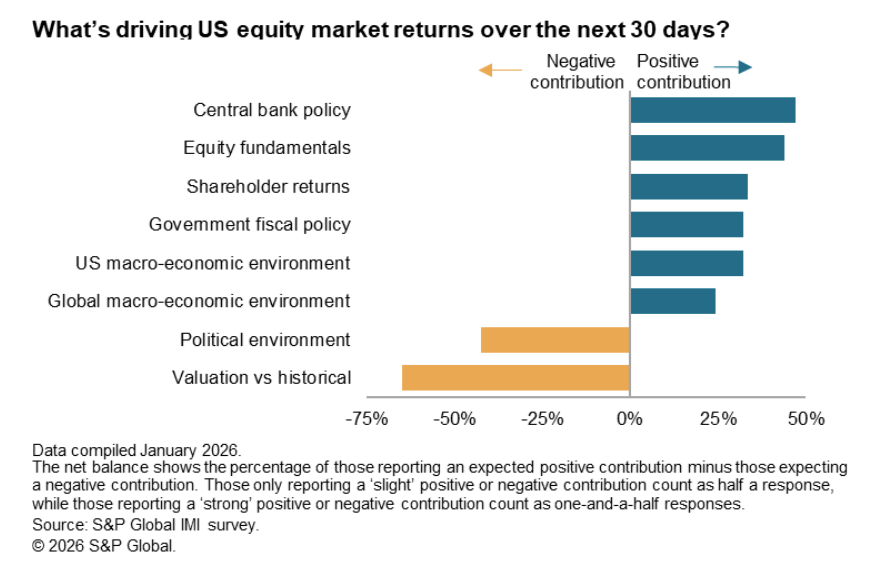
The report attributes the improvement partly to a brighter macro backdrop, with the U.S. economy viewed as a positive driver of equity returns to the strongest degree since just before Trump’s inauguration a year ago, and global growth influence seen as the strongest in just over four years.
-
Policy expectations remained supportive: the market contribution from lower interest rates was still described as among the highest since 2021, while fiscal policy was viewed as a positive equity driver to the greatest extent since August 2021.
-
Fund managers also reported improving views of equity fundamentals, with expectations for shareholder returns (dividends) the most positive in a year and earnings / fundamentals seen as the most positive in three years.
-
Valuations and politics remained the main drags on sentiment, but the negative impact of valuations eased to its lowest since June, while geopolitical concerns were described as less widespread than through much of 2025 despite renewed flare-ups.
-
Optimism broadened across asset classes, with sentiment improving for global equities (most bullish, highest since April 2021) and commodities (highest since April 2022), while sentiment also moved back into bullish territory for both corporate and sovereign debt.
-
Sector preferences in the near-term U.S. equity outlook were strongest for financials and healthcare, with industrials and basic materials moving sharply higher in rankings amid improved growth prospects; real estate and consumer staples remained bearish, while energy turned bullish for the first time in nine months.