


NFIB Small Business Optimism: January 2026
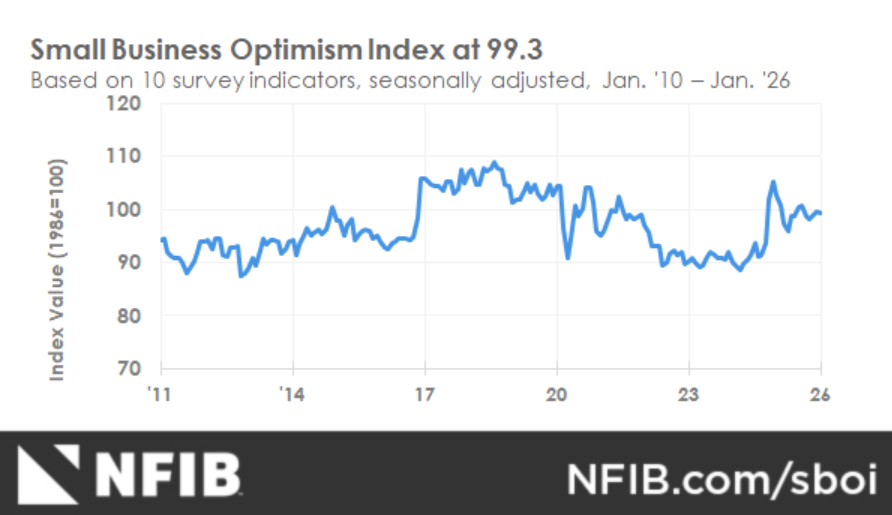
The NFIB Small Business Optimism Index edged down -0.2 pts to 99.3 in January 2026, staying above its 52-year average of 98 amid rising uncertainty.
-
Expected real sales volume rose +6 pts to a net 16% (SA), the only component with a substantial change, pointing to a firmer near-term demand outlook versus December.
-
The Uncertainty Index jumped +7 pts to 91, driven mainly by more owners unsure whether it is a good time to expand, indicating heightened hesitation despite optimism staying elevated.
-
Thirteen percent cited the cost or availability of insurance as their single most important problem (+4 pts), the highest share since December 2018, showing a notable rise in this constraint.
-
Sixty percent reported capital outlays in the past six months (+4 pts, highest since Nov 2023), while planned capital outlays slipped to 18% (SA, -1 pt), a level described as historically weak.
-
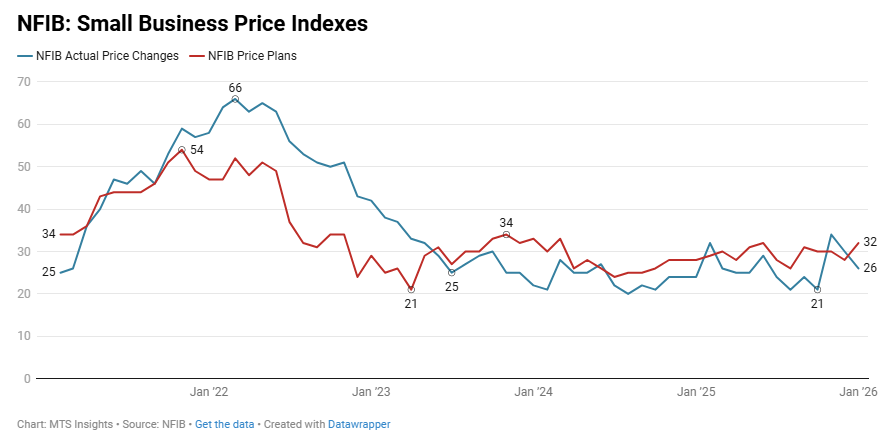
The net share raising average selling prices fell -4 pts to 26% (SA), still well above the historical average of 13%, while planned price increases rose to a net 32% (+4 pts), suggesting near-term pricing intentions firmed despite easing recent increases.
-
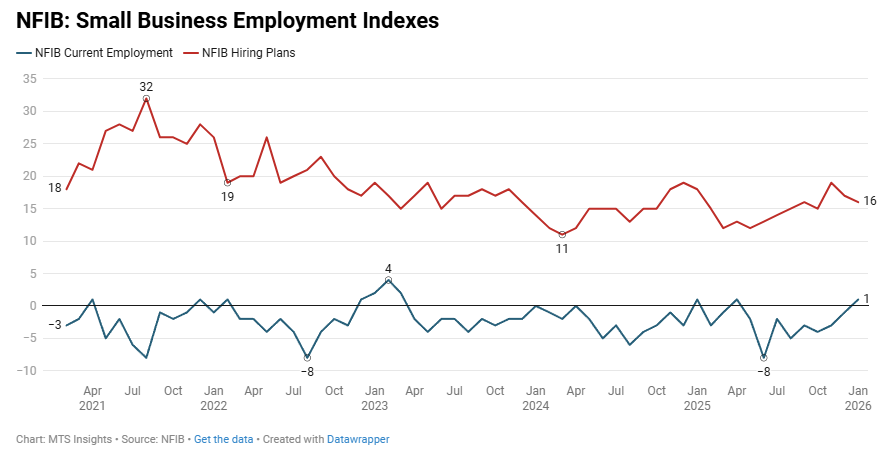
The Current Employment index improved to a net 1% (SA, +2 pts), the highest reading since April 2025 after dipping to cycle lows in Q2 and Q3 2025.
-
Unfilled job openings eased to 31% (SA, -2 pts) but remained above the 24% historical average, with 88% of hiring firms reporting few or no qualified applicants, while job creation plans dipped to a net 16% (SA, -1 pt).
-
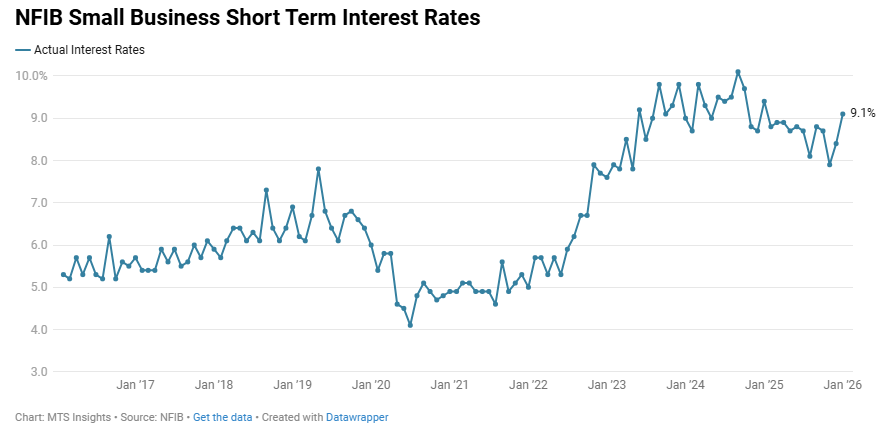
A net -6% reported paying a higher interest rate on their most recent loan (-3 pts), indicating some easing in credit conditions, even as the average short-maturity loan rate rose to 9.1% (+0.7 pts).
-
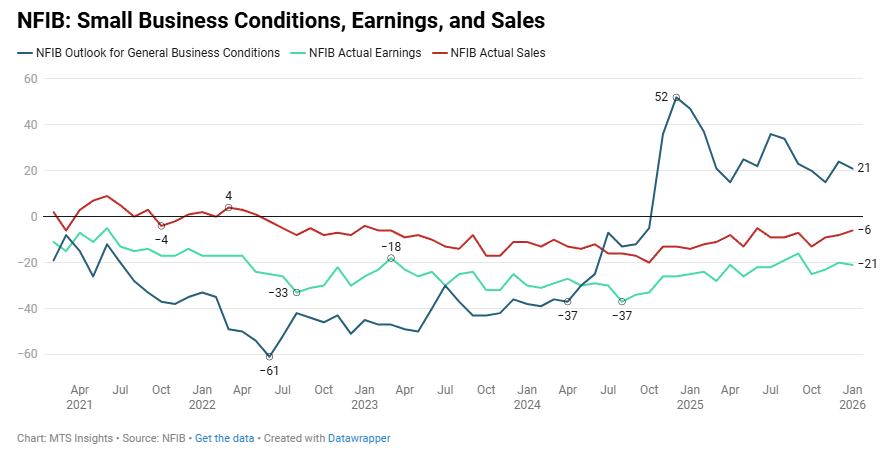
Business health improved, with 14% rating conditions as excellent (+5 pts) and 27% as fair (-7 pts), while expectations for better business conditions slipped to a net 21% (SA, -3 pts), pointing to stronger current assessments but slightly softer forward-looking views.