


NFIB Small Business Optimism: February 2026
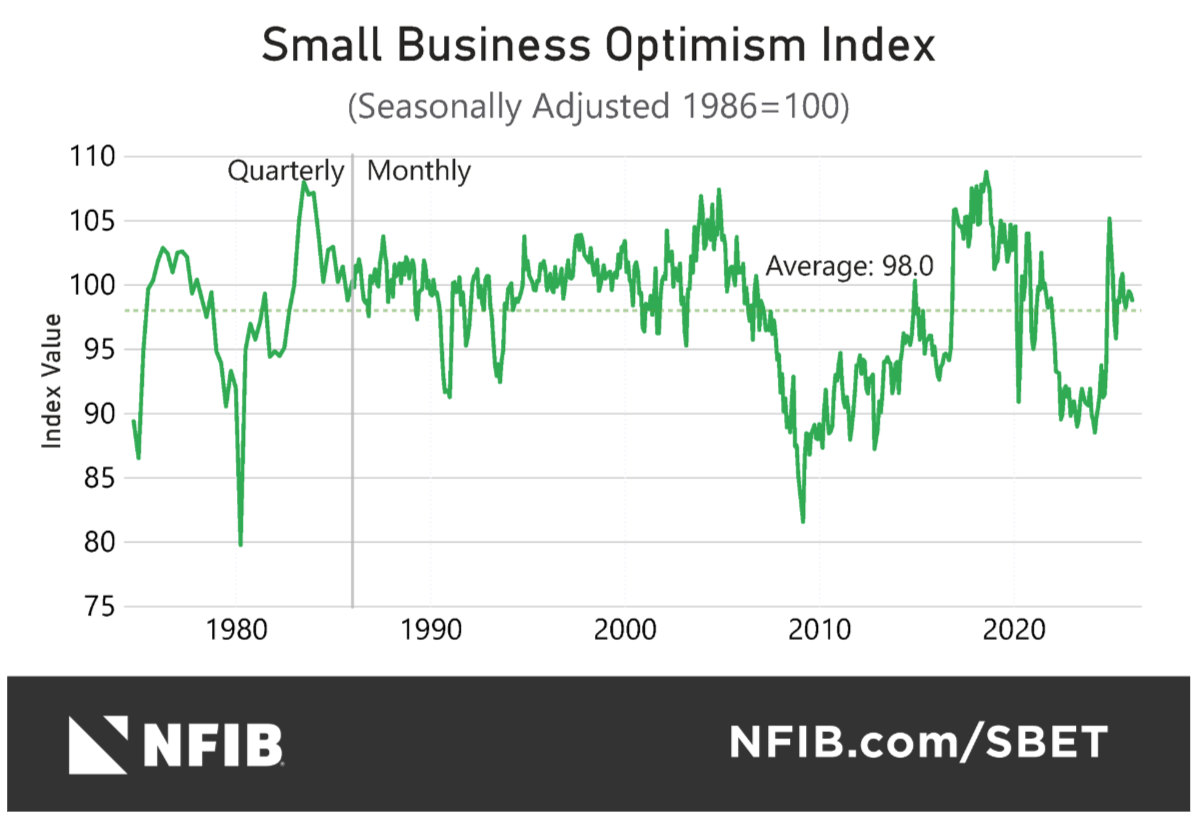
The NFIB Small Business Employment Index rose to 103.5 in February (+~1 pt MoM), standing 3.5 pts above its historical average and indicating continued tightness in the small business labor market.
-
The Employment Index increased to 103.5 (+~1 pt MoM), placing it 2.3 pts above the 2025 average and 3.5 pts above the historical average of 100, indicating that labor demand among small businesses remains elevated relative to long-term norms.
-
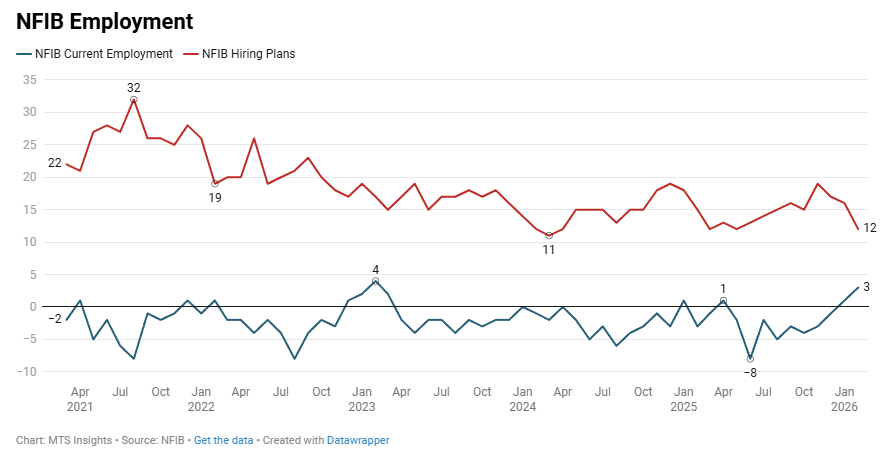
A total of 33% of small business owners reported job openings they could not fill (+2 pts MoM), including 28% with openings for skilled workers (+3 pts) and 10% with openings for unskilled labor (unchanged), highlighting persistent hiring challenges.
-
Hiring activity remained elevated, with 54% of owners reporting they hired or tried to hire in February (+4 pts MoM), though 46% of firms attempting to hire reported few or no qualified applicants, suggesting continued labor supply constraints.
-
A net 12% of owners plan to create new jobs in the next three months (-4 pts MoM), the lowest since May 2025 but still near the historical average of 11%, indicating softer but still positive hiring intentions.
-
Compensation pressures remained firm as a net 34% of owners reported raising compensation (+2 pts MoM), the highest reading since March 2025, while a net 22% plan to raise compensation in the next three months (unchanged).
-
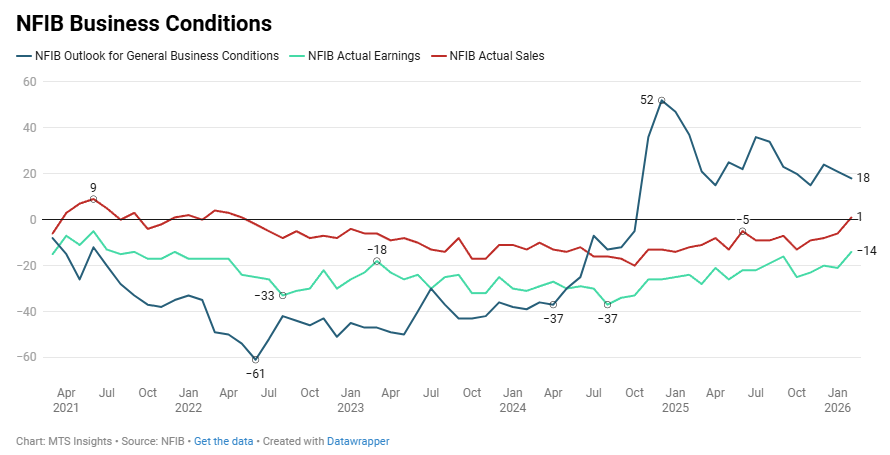
Sales conditions improved modestly, with a net 1% reporting higher nominal sales over the past three months (+7 pts MoM), bringing the reading close to the historical average of 0% and the strongest since May 2022.
-
However, forward-looking demand expectations weakened as the net share expecting higher real sales volumes fell to 8% (-8 pts MoM), reversing the gain seen in January.
-
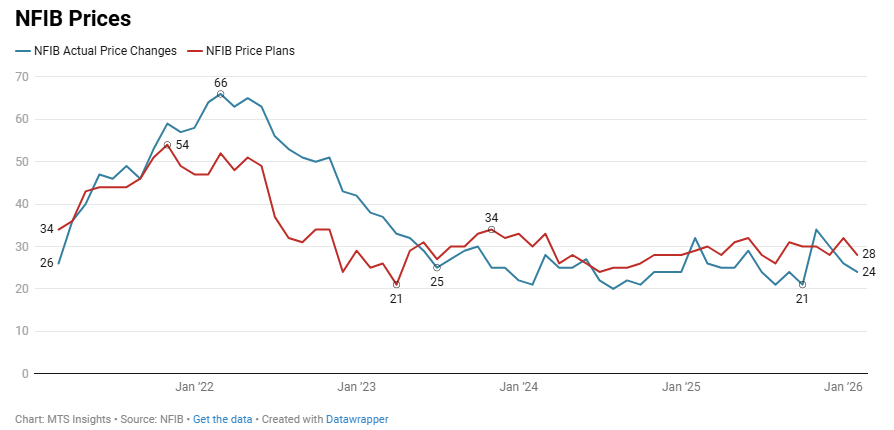
Price pressures eased slightly as a net 24% of owners raised average selling prices (-2 pts MoM) and a net 28% plan price increases in the coming months (-4 pts MoM), though both measures remain above historical averages.
-
Profit trends improved as the net share reporting positive earnings trends rose 7 pts to -14%, the strongest reading since December 2021, while business condition expectations declined to a net 18% (-3 pts MoM) but remained well above the historical average of 4%.