
AAR Rail Industry Overview: February 2026
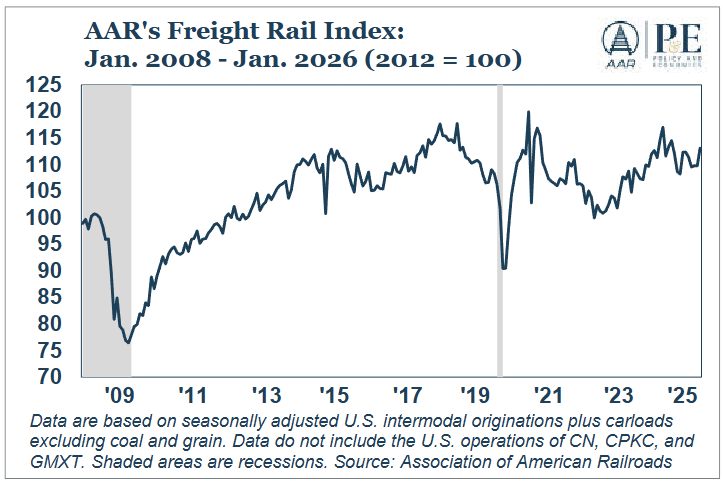
The AAR Freight Rail Index rose +3.1% MoM in January 2026, reflecting a short-term pickup in economy-sensitive rail volumes driven mainly by stronger carloads.
-
Coal carloads rose +4.7% YoY in January (+10.5k carloads), the largest monthly gain since May 2025, with YoY increases in 8 of the last 11 months amid short-term economic, weather, and policy support.
-
U.S. carloads excluding coal increased +4.3% YoY, marking the 21st YoY gain in the past 24 months, though gains remained modest alongside sluggish industrial and manufacturing activity.
-
Grain carloads averaged 24,355 per week, up +17.0% YoY and the highest since April 2021, reflecting stronger grain exports that remain central to overall rail volume growth.
-
Chemical carloads rose +2.4% YoY, their first increase after two monthly declines, following a record year in 2025 and indicating a firmer start to 2026.
-
Steel-related volumes were mixed: primary metal products fell -2.5% YoY (second decline in 11 months), iron and steel scrap surged +17.8% YoY (11th straight gain), and metallic ores fell -2.6% YoY for a 20th consecutive decline, highlighting structural shifts toward scrap-based steelmaking.
-
Railcars in storage totaled about 356k units (21.8% of the North American fleet) as of Feb. 1, with storage levels slowly increasing since mid-2025, signaling softer underlying transportation demand despite January’s rebound.