


Texas Service Sector Outlook Survey: November 2025
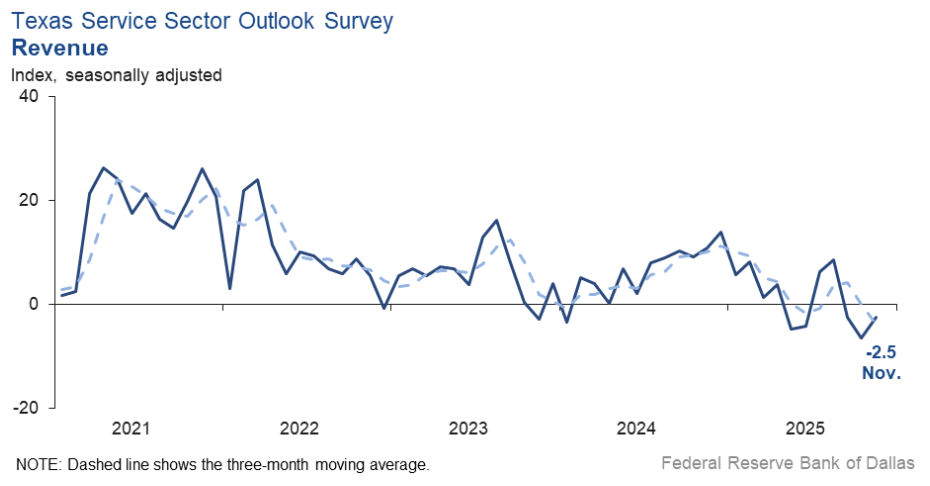
Texas service sector activity contracted slightly in November, with the Revenue Index rising to -2.5 (from -6.4 in October), marking a slower pace of decline and hinting at modest stabilization in activity.
-
Employment improved to 3.1 (from -5.8), reaching its highest level since November 2024 and indicating a return to modest job growth.
-
Hours Worked held nearly flat at -0.7 (from -1.4), showing little change in workweek length, while part-time employment remained steady at 0.2.
-
The General Business Activity Index rose to -2.3 (from -9.4), and Company Outlook improved to -4.2 (from -10.0), signaling reduced pessimism even as conditions remained weak.
-
Input Prices accelerated to 27.6 (from 23.0), and Selling Prices increased to 6.5 (from 4.6), pointing to firmer cost pressures and slightly stronger pricing power.
-
Wages and Benefits climbed to 14.7 (from 10.7), reflecting a pickup in labor cost growth.
-
Outlook Uncertainty decreased to 18.2 (from 22.2) but remained above the long-run average of 13.8, suggesting elevated but easing uncertainty.
-
Future activity indicators stayed positive, with the Future Revenue Index near 34.0 and the Future General Business Activity Index rising to 13.0, indicating continued expectations for growth in the months ahead.
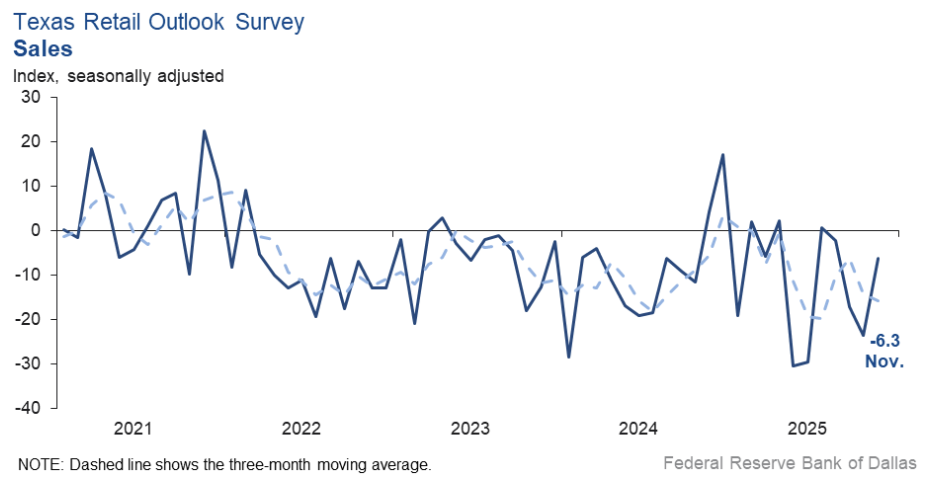
Texas retail activity contracted further in November, with the Sales Index rising to -6.3 from -23.5, marking a smaller decline but still indicating subdued demand across the sector.
-
Retail inventories increased sharply, with the Inventories Index up 7.4 (from 0.1), pointing to a buildup despite weaker sales.
-
Employment strengthened, as the Employment Index rose to 3.5 (from -15.3), and part-time employment improved to 6.8 (from -3.2), both now above their series averages.
-
Hours worked held steady at -7.7 (from -6.8), showing that retailers continued to trim work hours even as hiring picked up.
-
Wage pressures eased notably, with the Wages and Benefits Index falling to 6.1 (from 13.3), compared with little change in selling prices at 16.2.
-
Input prices moderated to 27.8 (from 30.6) but remained above the long-run average, indicating ongoing cost pressures.
-
Broader conditions remained weak; the General Business Activity Index improved to -12.6 (from -23.7), and the Company Outlook Index rose to -12.4 (from -22.3), though both stayed deeply negative.
-
Outlook uncertainty declined to 13.2 (from 17.3) but remained above the series average, reflecting continued caution among retailers.
-
Future retail expectations stayed positive overall, with the Future Sales Index at 6.9 (though down 16 points), and the Future General Business Activity Index steady at 4.1.