


Texas Service Sector Outlook Survey: December 2025
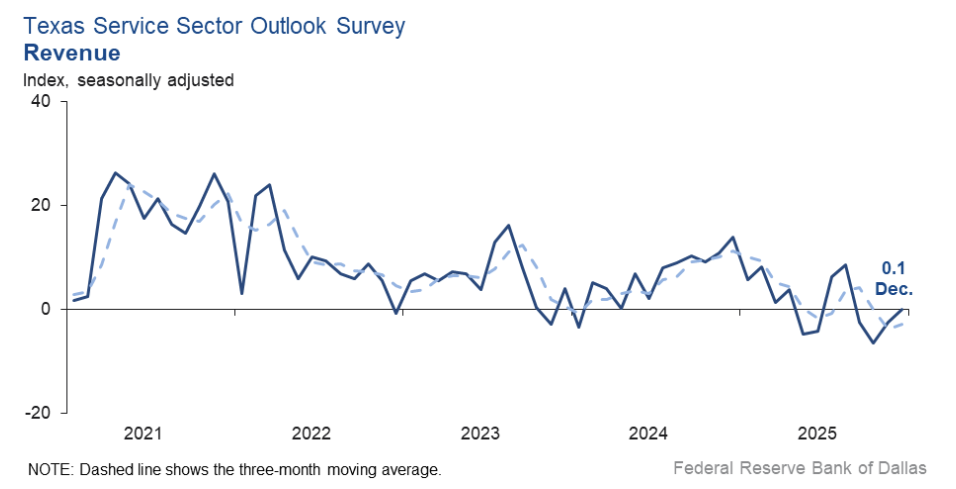
Texas service sector activity was flat in December, with the Revenue Index edging up 2.6 pts to 0.1, signaling unchanged conditions after weakening in November.
-
Labor indicators showed little change in head counts, as both the Employment Index (-0.8) and Part-Time Employment Index (-0.8) hovered near zero, suggesting broadly stable staffing levels.
-
Hours Worked declined further, with the index falling to -2.4, pointing to a modest contraction in workweeks despite steady employment.
-
Broader sentiment weakened slightly, with the General Business Activity Index at -3.3 and the Company Outlook Index at -2.9, keeping overall conditions in negative territory.
-
Outlook Uncertainty eased to 15.9 (from 18.2) but remained above the series average of 13.8, indicating elevated uncertainty despite a modest improvement.
-
Cost pressures were little changed, as the Input Prices Index held near recent levels at 26.2 and the Selling Prices Index came in at 7.9, similar to November.
-
Wage growth slowed, with the Wages and Benefits Index declining to 10.8 from 14.7, indicating softer labor cost pressures late in the year.
-
Forward-looking indicators stayed positive, with the Future Revenue Index at 35.3 and the Future General Business Activity Index at 12.0, suggesting expectations for higher activity in the months ahead.
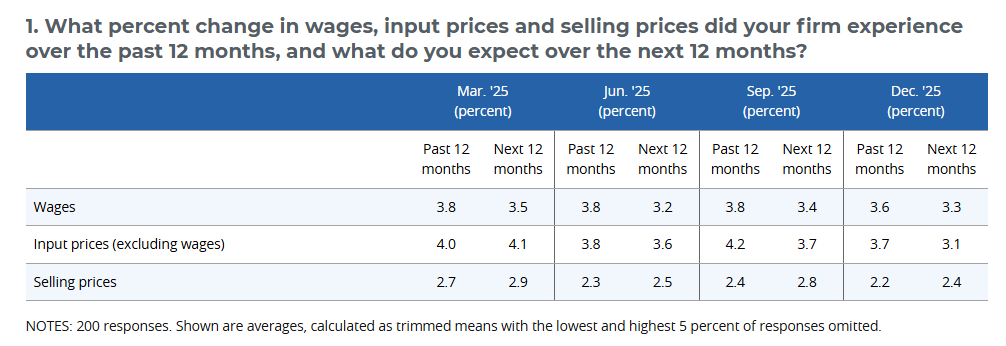
- Expected input and output price growth in the service sector continued to slow in the latest special question to the lowest growth rates this year.
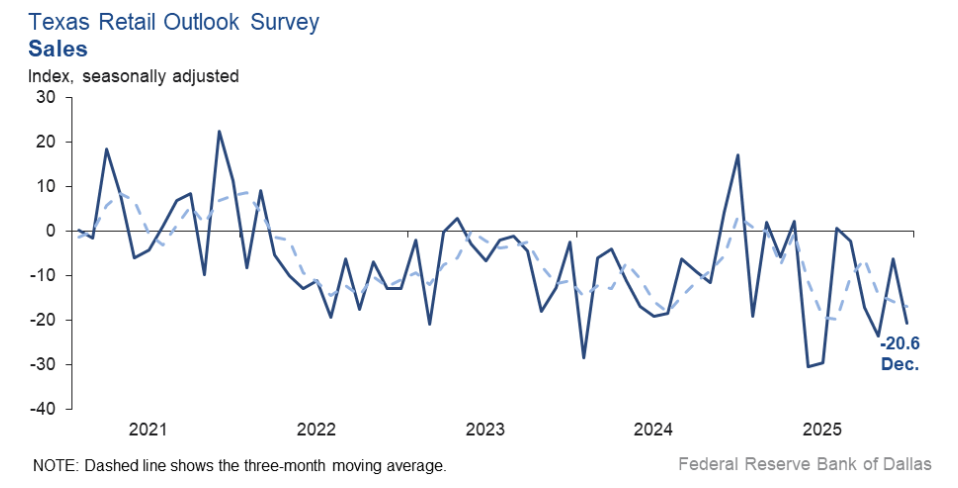
Texas retail sales fell sharply in December, with the Sales Index dropping -14.3 pts to -20.6, reflecting a significant contraction in retail activity.
-
Inventory levels were unchanged, with the Inventories Index at 0.0, indicating neither stock accumulation nor drawdown despite weaker sales.
-
Labor market conditions softened, as the Employment Index fell to -6.2 (-9.7 pts MoM) and the Part-Time Employment Index dropped to 0.0, suggesting reduced hiring momentum.
-
Hours Worked remained weak at -6.3, showing continued contraction in workweeks broadly in line with the prior month.
-
Broader sentiment worsened, with the General Business Activity Index falling to -15.9 and the Company Outlook Index declining to -15.4, both signaling deeper pessimism.
-
Outlook Uncertainty rose sharply to 21.1 (+7.9 pts MoM), moving further above its series average and indicating increased uncertainty among retailers.
-
Price pressures intensified, as the Selling Prices Index jumped to 28.2 (+12.0 pts) and the Input Prices Index climbed to 38.5 (+10.7 pts), while Wages and Benefits increased to 10.5.
-
Despite current weakness, future expectations improved, with the Future Sales Index rising to 18.8 and the Future General Business Activity Index holding near prior levels at 2.2.
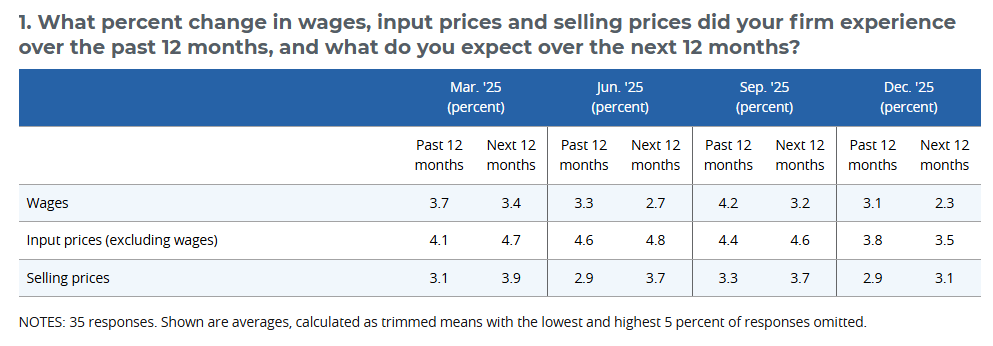
- Expected input and output price growth in the retail sector continued to slow in the latest special question to the lowest growth rates this year.