

J.D. Power Automotive Forecast: November 2025
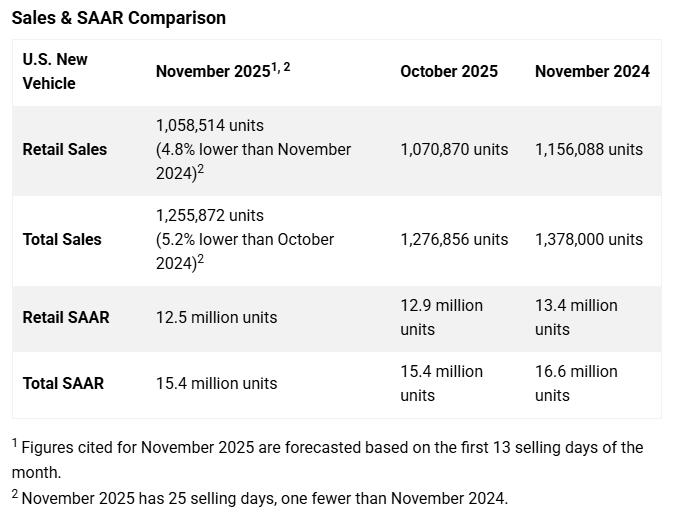
U.S. new-vehicle sales are forecast at 1.26M units in November 2025 (-5.2% YoY), with retail sales at 1.06M units (-4.8% YoY), reflecting continued payback from September’s EV pull-ahead ahead of expiring tax credits.
-
Total SAAR is expected at 15.4M units (Nov 2024: 16.6M), while retail SAAR is projected at 12.5M (Nov 2024: 13.4M), showing a slower underlying sales pace.
-
EV retail share is forecast at 6.0% (Sep: 12.9%; Nov 2024: 9.6%), while ICE share rises 2.3 ppt YoY to 77.5%, indicating a significant shift back toward conventional vehicles.
-
Average transaction prices are expected at $46,029 (+1.6% YoY), and average monthly finance payments at $760 (+$19 YoY), highlighting ongoing affordability pressures.
-
Incentive spending averages $3,211 (-$125 YoY), with EV discounts at $11,869 (+$260 YoY) and non-EV discounts at $2,960 (+$161 YoY), showing diverging pricing strategies.
-
Fleet sales are projected at 197,358 units (-7.5% YoY), representing 15.7% of total sales (-0.4 ppt YoY).
-
Retail inventory rises to 2.29M units (+11.7% YoY), equal to 64 days of supply (+5 days YoY), signaling gradually improving availability.
-
Used-vehicle prices average $29,696 (+$725 YoY), while average trade-in equity dips to $7,822 (-$111 YoY), with negative equity rising to 26.9% (+3.3 ppt YoY).
-
Retail buyers are expected to spend $46.8B on new vehicles (-6.4% YoY), while retailer profit per unit edges up to $2,161 (+$6 YoY).