

J.D. Power Automotive Forecast: October 2025
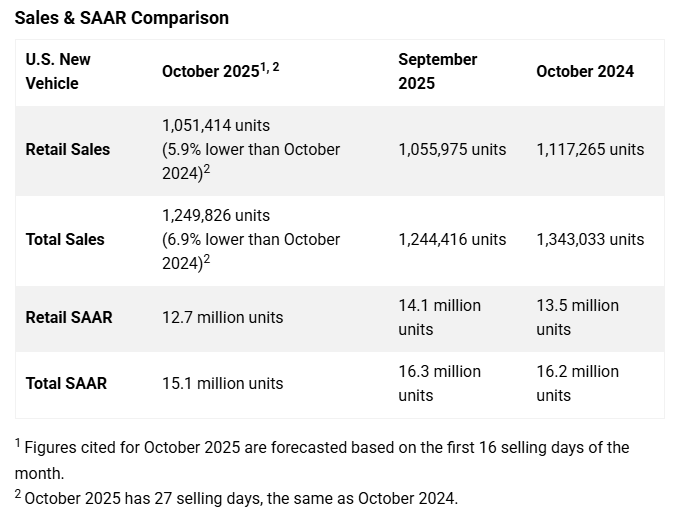
U.S. new-vehicle sales are forecast at 1.25M units in October 2025 (-6.9% YoY), with retail sales at 1.05M units (-5.9% YoY), reflecting a sharp pullback following last month’s EV-driven surge from pre-expiration tax credit purchases.
-
The total SAAR is expected at 15.1M units (Sep: 16.3M; Oct 2024: 16.2M), while retail SAAR is 12.7M (Sep: 14.1M; Oct 2024: 13.5M).
-
EVs are projected to account for just 5.2% of retail sales, down -7.7 ppt MoM and -3.4 ppt YoY, reversing September’s pre-credit pull-forward; ICE share rose to 79.2% (+2.4 ppt YoY).
-
Fleet sales are forecast at 198K units (-12.1% YoY), representing 15.9% of total sales (-0.9 ppt YoY).
-
Average retail transaction price rose +2.2% YoY to $46,057, while incentive spending fell -$444 YoY to $2,674 (5.3% of MSRP, -1 ppt YoY).
-
EV discounts averaged $13,161 (+$2,211 YoY), partially offsetting the loss of the federal credit; non-EV incentives fell to $2,423 (-$282 YoY).
-
Average monthly finance payments reached $758 (+$21 YoY), while average loan rates eased slightly to 6.56% (-14 bps YoY).
-
Retail inventory rose +11.5% YoY to 2.27M units, equal to 61 days of supply (up from 59 days).
-
Used-vehicle prices averaged $29,446 (+$473 YoY), and average trade-in equity rose to $8,378 (+$386 YoY), though 26.6% of trade-ins carried negative equity (+2.2 ppt YoY).
-
Total consumer spending on new vehicles is expected at $46.1B (-4.2% YoY), while total retailer profit per unit rose to $2,295 (+$97 YoY).