

EIA Short-Term Energy Outlook: November 2025
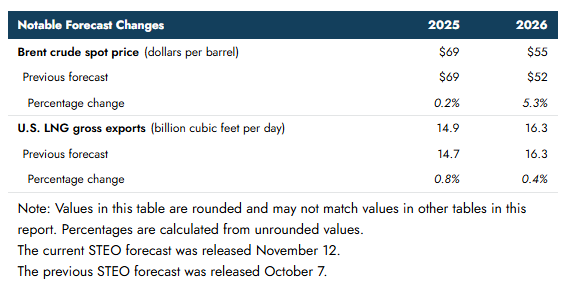
The EIA’s November STEO slightly raised 2026 energy price and export projections while maintaining expectations for broadly softer oil markets and steady LNG growth.
-
Brent crude is forecast to average $69/b in 2025 (unchanged) and $55/b in 2026 (+5.3% vs prior forecast), as updated assumptions on Chinese inventories and Russian sanctions temper expected price declines.
-
U.S. LNG exports are projected at 14.9 Bcf/d in 2025 (+0.8% vs prior) and 16.3 Bcf/d in 2026 (+0.4%), reflecting faster-than-expected ramp-up at Plaquemines LNG and continued export capacity expansion.
-
The EIA expects global oil inventories to rise through 2026, keeping prices under pressure despite the modest upward revision to Brent.
-
U.S. gasoline and diesel prices are forecast to decline through 2026, with gasoline averaging below $3.00/gal (-10% vs 2024) and diesel $3.50/gal (-7%), tracking lower crude benchmarks.
-
Henry Hub natural gas is projected to average $3.90/MMBtu in winter 2025–26 and $4.00 in 2026 (+16% YoY), driven by higher LNG exports amid flat production growth.
-
Electricity demand is expected to rise +2.4% in 2025 and +2.6% in 2026, led by strong load growth in Texas and the West South Central region from data centers and crypto mining.
-
Coal production is forecast to remain above 500 MMst in 2026, about 15 MMst higher than previously projected, supported by mine reopenings in Appalachia and slower inventory drawdowns.