

EIA Short-Term Energy Outlook: October 2025
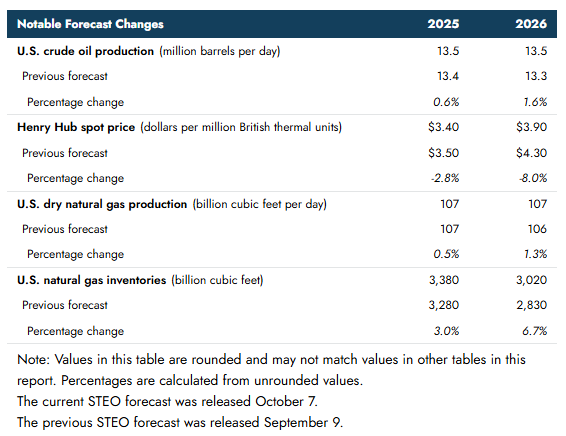
U.S. crude oil and natural gas forecasts were revised modestly in the latest STEO, reflecting higher starting production levels and rising inventories alongside lower price expectations for 2026.
-
U.S. crude oil production is forecast at 13.5 mb/d in both 2025 and 2026, up 0.6% and 1.5% respectively from prior forecasts. July output reached a record high above 13.6 mb/d, prompting upward revisions, especially in the Gulf of Mexico.
-
Henry Hub spot price is now projected at $3.40/MMBtu in 2025 (-2.8% vs prior) and $3.90 in 2026 (-8.0%), reflecting expectations of higher domestic supply and storage.
-
U.S. dry natural gas production remains steady at 107 Bcf/d for both 2025 and 2026, with small upward revisions (+0.5% and +1.3%) tied to expanding LNG capacity and continued drilling efficiency.
-
U.S. natural gas inventories are forecast at 3,380 Bcf in 2025 (+3.0%) and 3,020 Bcf in 2026 (+6.7%), signaling higher storage levels from robust output.
-
Global oil prices are expected to decline, with Brent crude averaging $62/b in Q4 2025 and $52/b in 2026, as global supply growth—particularly from non-OPEC+ producers—drives inventory accumulation.
-
LNG export capacity is set to rise by 5 Bcf/d through 2026, lifting total exports to 16.3 Bcf/d, led by new projects at Plaquemines and Corpus Christi.
-
Coal consumption in the power sector rose 15% YoY in 1H25 but is expected to slow to +4% in 2H25 before falling -3% in 2026, as solar generation expands despite firmer gas prices.