

EIA Short-Term Energy Outlook: December 2025
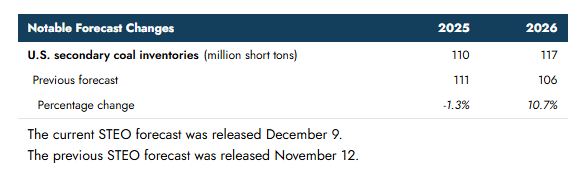
The EIA’s December STEO projects Brent crude to average $55/b in early 2026 (little changed) and Henry Hub natural gas to average almost $4.30/MMBtu this winter (+$0.40 vs the November forecast), reflecting colder weather and rising inventories as key drivers of the near term outlook.
-
Global oil inventories are expected to continue rising through 2026, keeping downward pressure on crude prices, though OPEC+ production restraint and China’s ongoing inventory builds are expected to limit the scale of price declines.
-
Henry Hub natural gas prices were revised up for winter 2025–26, with the spot price now forecast near $4.30/MMBtu due to colder than expected December weather; prices are projected to ease to about $4.00/MMBtu in 2026 as milder early year temperatures and rising output temper demand.
-
U.S. electricity generation is forecast to grow +2.4% in 2025 and +1.7% in 2026, driven largely by surging data center demand in ERCOT and PJM regions; the 2026 forecast is lower than last month’s due to a slower observed pace of large load additions.
-
Coal consumption is expected to increase +9% in 2025, led by an +11% rise in electric power sector usage amid higher natural gas costs and stronger electricity demand; consumption is projected to decline in 2026 as renewable generation expands.
-
Coal production is expected to fall by less than consumption in 2026, supporting modest growth in exports and contributing to rising secondary coal inventories.
-
The STEO raises 2026 U.S. secondary coal inventories to 117 million short tons (+10.7% vs prior forecast), while the 2025 inventory projection was trimmed to 110 million short tons (-1.3%), reflecting updated expectations for supply balances heading into the mid 2020s.