


Bank of England Monetary Policy Decision: July 2026
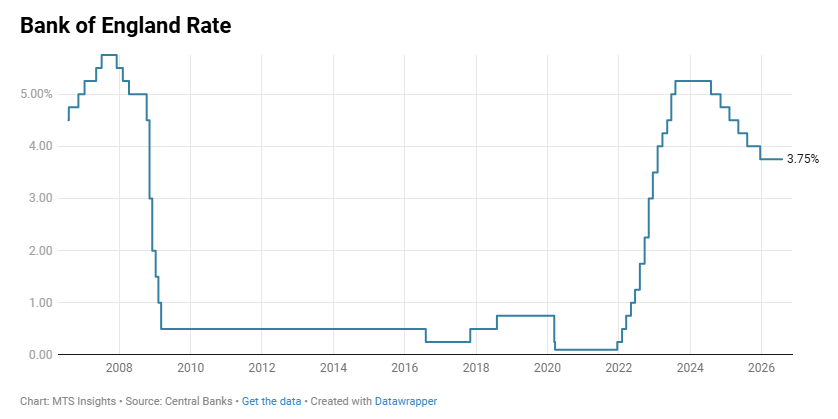
The Bank of England voted 6–3 to hold Bank Rate at 3.75%, with three members favoring a +25 bps hike to 4.00%, indicating a cautious majority amid upside inflation risks from energy prices.
-
CPI inflation fell to +2.6% YoY in June, supported by continued moderation in services and food inflation, although it remained above the 2% target and was expected to rise later in 2026 as higher energy costs passed through.
-
Brent crude and UK natural gas futures stood at $84 per barrel and 136 pence per therm on 28 July, both materially above pre-conflict levels, while motor fuels contributed +0.6 ppts to June CPI inflation.
-
The MPC judged inflation risks to be tilted to the upside, reflecting the possibility of renewed conflict escalation, persistently elevated energy prices, and stronger second-round effects in wage and price setting.
-
There was little evidence so far of material second-round effects, with inflation expectations, firms’ pricing expectations, wage-price feedback, and food inflation showing limited deterioration, although the Committee stressed that such effects may emerge with a lag.
-
Domestic inflation pressures continued to ease as wage growth slowed, the labour market loosened, demand remained soft, and financial conditions tightened materially for households and businesses compared with pre-conflict levels.
-
Six members favored holding Bank Rate, judging that the current stance and tighter financial conditions provided sufficient protection against upside risks while preserving flexibility to respond if inflation persistence increased.
-
Three members preferred a +25 bps increase to 4.00%, arguing that a proactive move would reduce the risk of second-round effects and that the cost of tightening too early would be lower than responding too late.
-
The MPC remained ready to adjust policy in either direction, with additional restraint possible if second-round effects emerged and renewed rate cuts possible if upside risks subsided and underlying disinflation continued.