

Bank of England Monetary Policy Decision: September 2026
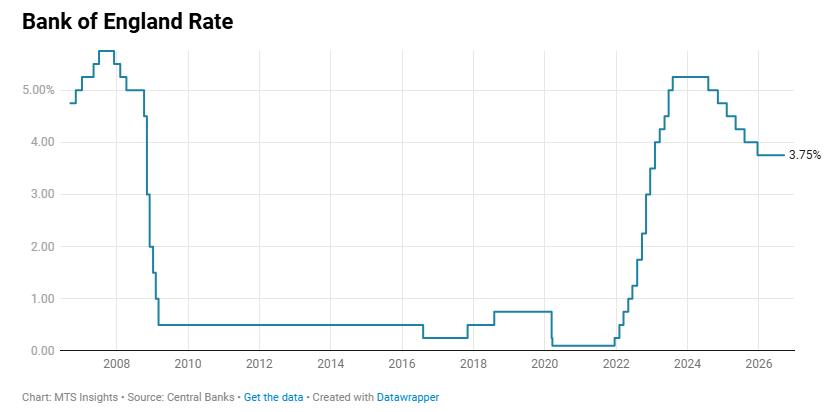
The Bank of England voted 6-3 to hold Bank Rate at 3.75%, with three members favoring a +25 bps hike to 4.00%, as CPI inflation rose to +3.1% YoY in August and higher energy prices increased upside risks to the inflation outlook.
-
CPI inflation increased to +3.1% YoY in August, with around +0.7 ppts of the +1.1 ppt overshoot relative to the 2% target attributed directly to energy prices, primarily motor fuels. Services inflation held at +3.4% YoY, down from +4.5% in March, while underlying inflation measures remained above target-consistent rates.
-
Energy pressures intensified further, with Brent crude and UK wholesale gas prices up +36% and +78%, respectively, since the July Monetary Policy Report, reaching $106 per barrel and 207 pence per therm on September 14. The MPC said the Middle East conflict had become more protracted, increasing the likelihood of a higher and more volatile near-term inflation path.
-
CPI inflation is now expected to rise to around +3.75% YoY in Q4 2026, up from the +3.2% projection in July, before reaching slightly above +4% in Q1 2027. Recent increases in wholesale oil, gas, and electricity costs accounted for almost all of the upward revision to the near-term outlook.
-
There remained little evidence of material second-round effects in wages and prices, while indirect energy pass-through had been smaller than initially expected. However, the MPC judged that the risk of second-round effects had increased since July and could rise further if elevated energy prices persisted, particularly as above-target inflation coincides with upcoming wage-setting decisions.
-
Economic activity proved more resilient than expected, with GDP growing +0.4% QoQ in Q2, +0.1 ppt above the July forecast, and +0.4% MoM in July. Staff raised their Q3 GDP estimate to +0.4% QoQ from +0.1%, although business surveys continued to indicate somewhat weaker growth.
-
Labour market conditions remained soft, with unemployment at 4.9% in the three months to July and private-sector regular wage growth easing to +2.9% YoY from +3.3% at the start of 2026. Other indicators suggested underlying private-sector wage growth of around +3.5%, slightly above the Bank's estimate of a target-consistent rate.
-
Six MPC members favored holding Bank Rate at 3.75%, judging that tight financial conditions and domestic economic slack continued to restrain inflation despite increasing upside risks. Three members preferred a +25 bps hike to 4.00%, arguing that stronger activity, potentially stabilizing slack, and the risk of second-round effects warranted a proactive tightening to help anchor inflation expectations.
-
The MPC unanimously adopted a multi-year plan to reduce its monetary-policy gilt holdings to zero, with £368 billion remaining after £120 billion is set aside to back banknote issuance. The portfolio will decline by an average £46 billion annually through September 2034, combining £20 billion of annual active sales with maturing gilts.