

J.D. Power Automotive Forecast: January 2026
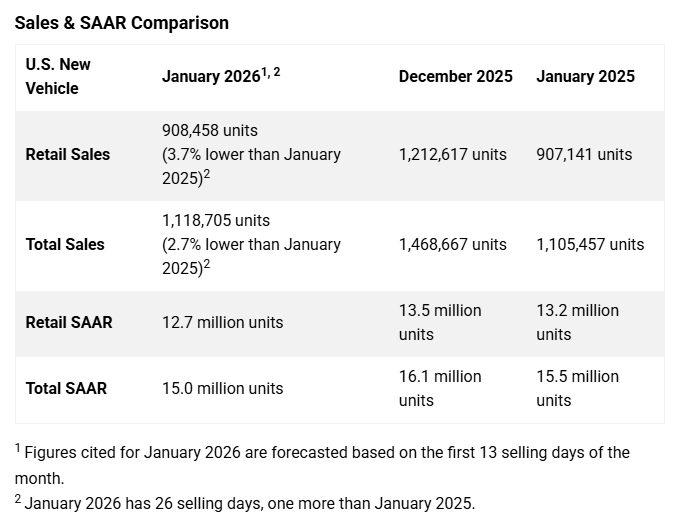
U.S. new-vehicle sales are forecast at 1.12M units in January 2026 (-2.7% YoY), reflecting a modestly softer start to the year.
-
Total new-vehicle sales (retail + non-retail) are projected at 1,118,700 units (-2.7% YoY), though on an unadjusted selling-day basis sales are +1.2% vs January 2025 due to one extra selling day (26 vs 25).
-
Total SAAR is expected at 15.0M units, down from 15.5M in January 2025 and down from 16.1M in December 2025, indicating weaker annualized momentum entering 2026.
-
Retail new-vehicle sales are projected at 908,500 units (-3.7% YoY), with retail SAAR at 12.7M (vs 13.2M in January 2025 and 13.5M in December 2025).
-
EVs are expected to account for 6.6% of retail sales (-2.9 ppts YoY), while ICE vehicles rise to 77.7% (+2.7 ppts YoY) and HEVs increase to 14.7% (+1.4 ppts YoY), showing a mix shift toward ICE/hybrids.
-
Average retail transaction prices are expected at $45,880 (+1.1% YoY), with non-EV prices at $45,510 (+0.9% YoY) and EV prices at $51,981 (+18.1% YoY), highlighting a sharp relative increase for EV pricing.
-
Average monthly finance payments are projected at $760 (+$24 YoY), while the average new-vehicle loan rate is 6.29% (-48 bps YoY); 84-month loans are expected to rise to 11.7% of financed sales (vs 9.9% a year ago), underscoring affordability strain.
-
Incentive spending averages $3,192 per vehicle (+$25 YoY), with EV discounts at $11,212 (-$1,820 YoY) versus non-EV discounts at $3,004 (+$403 YoY), reflecting lower EV discounting alongside stronger incentives on ICE vehicles.
-
Retail inventory is estimated at 2.12M units (-1.4% YoY), equal to 59 days of supply (+2 days YoY), while dealer profit per unit is projected at $2,148 (-$62 YoY; +$224 vs December) and total retailer profit at $1.9B (-2.6% YoY).