


US GDP: Q3 2025 (Final Estimate) (DELAYED)
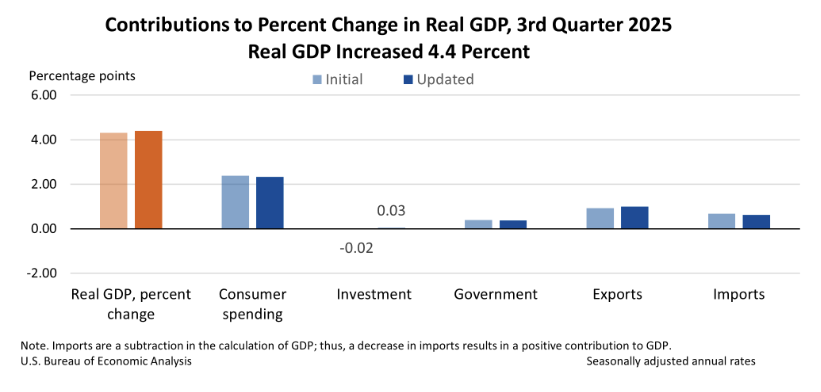
U.S. real GDP growth in Q3 2025 was revised up to +4.4% SAAR (from +4.3% SAAR initial), reflecting slightly stronger top-line momentum than first reported.
-
The +4.4% SAAR increase in Q3 (vs +3.8% in Q2) was driven by gains in consumer spending, exports, government spending, and investment, while imports fell (imports subtract from GDP).
-
The +0.1 ppt upward revision to GDP primarily reflected upward revisions to exports and investment, partly offset by a downward revision to consumer spending; imports were revised up.
-
Real final sales to private domestic purchasers rose +2.9% SAAR, revised down -0.1 ppt from the prior estimate, indicating slightly softer underlying private domestic demand than initially reported.
-
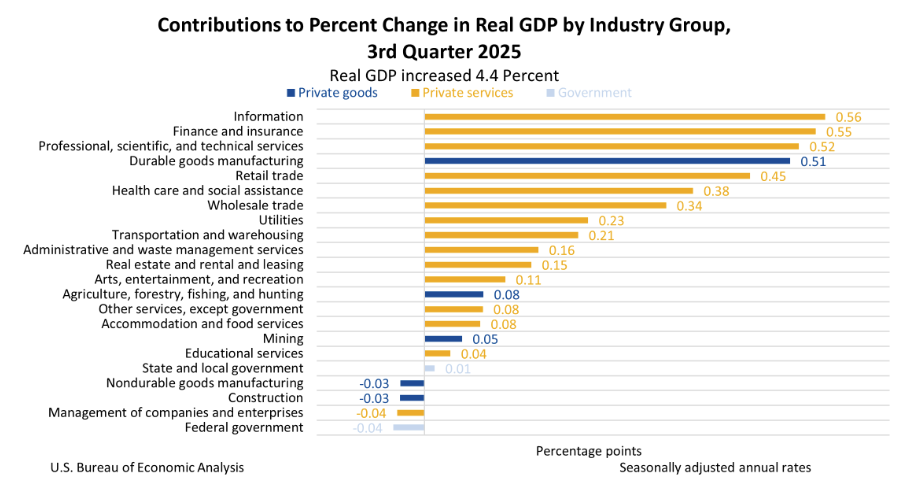
From an industry view, real GDP gains reflected a +5.3% increase in real value added for private services-producing industries and a +3.6% increase for private goods-producing industries, partly offset by a -0.3% decline in government value added.
-
Real gross output increased +3.2% SAAR, with private services up +4.4% and government up +2.1%, while private goods-producing industries declined -0.1%.
-
Inflation measures were unchanged from the initial estimate: gross domestic purchases price index +3.4%, PCE price index +2.8%, and core PCE price index +2.9%.
-
Real GDI increased +2.4% SAAR (unchanged), while the average of real GDP and real GDI was +3.4% (unchanged), keeping the combined output-income signal steady.
-
Corporate profits from current production rose +$175.6B, revised up +$9.5B, indicating somewhat stronger profit growth than first estimated.