

US CPI: December 2025
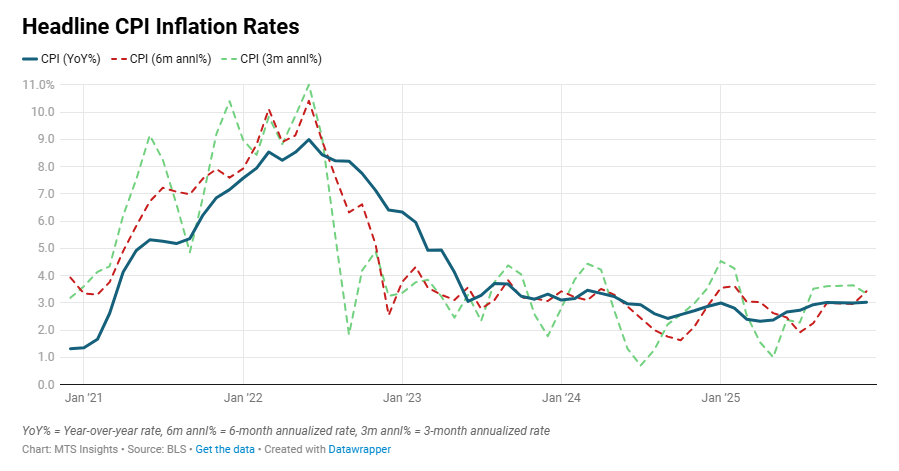
US CPI increased +0.3% MoM and +2.7% YoY in December, while core CPI rose +0.2% MoM and +2.6% YoY, showing steady headline inflation alongside continued cooling in underlying price pressures.
-
Headline CPI matched expectations, with the +2.7% YoY rate unchanged from November and consistent with mid-2025 readings, as offsetting moves in food and energy kept the top line stable.
-
Food rose +0.7% MoM, the largest monthly increase since October 2022, driven by food at home +0.7% MoM (highest since August 2022) with broad grocery strength (5 of 6 major indexes rising); “other food at home” +1.6% MoM stood out, led by items like fats & oils (+1.8% MoM) and spices/condiments/sauces (+1.9% MoM).
-
Food away from home also increased +0.7% MoM, matching the strongest monthly gain since October 2022 and adding to the breadth of food-related inflation in the month.
-
Energy rose a more modest +0.3% MoM, as utility natural gas services +4.4% MoM (largest since January 2023) was offset by gasoline -0.5% MoM (NSA gasoline index -5.3% MoM) and electricity -0.1% MoM, limiting overall energy pressure.
-
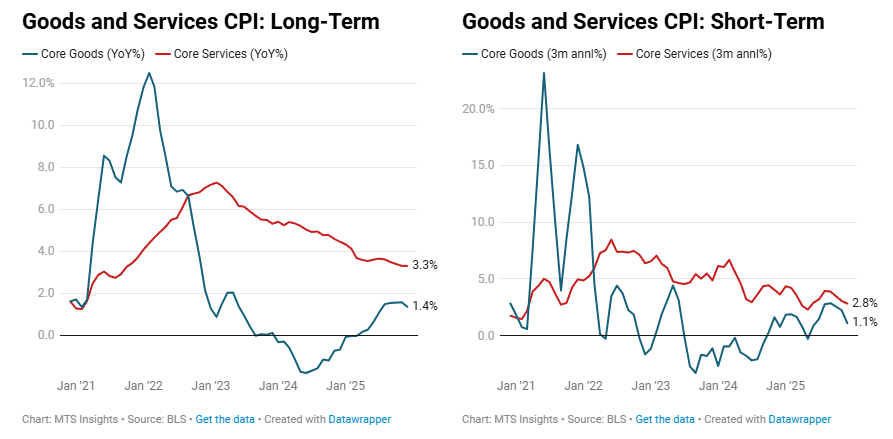
Core CPI undershot expectations, with the downside surprise attributed mainly to weaker goods inflation, while services remained firmer; the +2.6% YoY core rate was described as the lowest since March 2021, reinforcing a broader cooling trend.
-
Core goods were flat (0.0% MoM), the weakest since May 2025, as gains in household goods (+0.5% MoM) and apparel (+0.6% MoM) were offset by declines in transportation goods (-0.3% MoM) and education & communication goods (-2.0% MoM).
-
Vehicle prices were a key drag on core goods, with new vehicles 0.0% MoM and used cars & trucks -1.1% MoM (largest decline since July 2024), reinforcing the role of autos in recent core disinflation.
-
Core services rose +0.3% MoM, the strongest since August, led by shelter +0.4% MoM (also hottest since August) and a sharp rise in lodging away from home +2.9% MoM (strongest since September 2023); other notable increases included medical care services +0.4% MoM, transportation services +0.5% MoM, and recreation services +1.8% MoM (largest on record).
-
CPI excluding food, energy, used vehicles, and shelter rose +0.2% MoM and +2.3% YoY, which is only slightly above the Fed’s 2% target, supporting the view that underlying pressures were not accelerating.
-
There continues to be limited evidence of tariffs creating a broad inflation pickup: while household goods and apparel rose strongly in December, the 3-month annualized core goods inflation rate fell to 1.1%, the lowest since June, suggesting the near-term trend is turning down.