

US CPI: January 2026
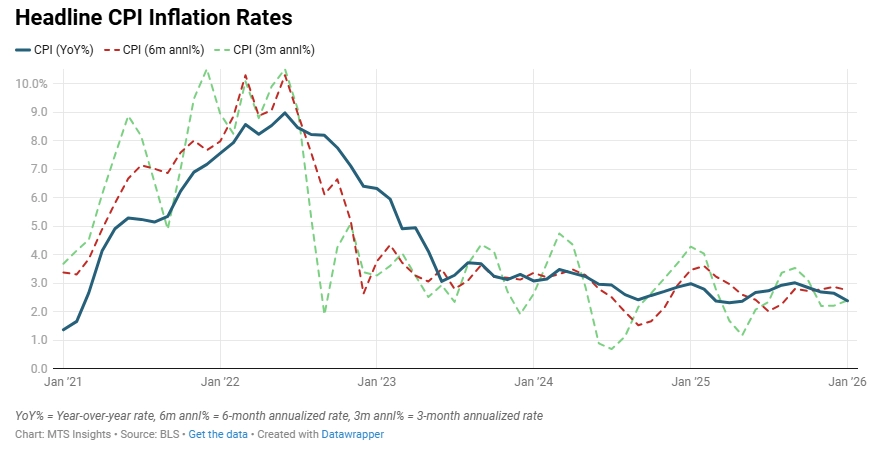
US CPI rose +0.2% MoM and +2.4% YoY in January (down from +2.7% YoY), reflecting softer headline inflation driven by volatile components.
-
Headline CPI increased +0.2% MoM (vs +0.3% expected), and the YoY rate slowed to +2.4% from +2.7% in December, marking the lowest since April 2025 and near the bottom of its post-2022 range.
-
Food prices rose +0.2% MoM (down from +0.7% MoM in December), with food at home +0.2% MoM, the slowest since July 2025, and food away from home +0.1% MoM, indicating limited price pressure despite broad grocery increases.
-
Energy fell -1.5% MoM, driven by energy goods -3.3% MoM, including gasoline -3.2% MoM and -7.5% YoY; energy services rose +0.2% MoM, with utility gas services +1.0% MoM, but had a small overall impact.
-
Core CPI increased +0.3% MoM and +2.5% YoY (down from +2.6% YoY), the lowest annual core rate since March 2021, as goods remained soft while services strengthened.
-
Core goods were flat (0.0% MoM) for a second month, with the YoY rate at +1.1% (lowest since June 2025); transportation goods fell -0.7% MoM, including used cars and trucks -1.8% MoM (largest since January 2024), while medical care goods declined -0.1% MoM and prescription drugs were -0.5% YoY.
-
Core services rose +0.4% MoM (largest since July 2025), with shelter +0.2% MoM and stronger gains in transportation services +1.4% MoM, other personal services +1.6% MoM, recreation +0.4% MoM, and education & communication +0.4% MoM; airfare jumped +6.5% MoM and internet services +1.8% MoM (largest ever).
-
Excluding energy, food, used vehicles, and shelter, CPI rose +0.5% MoM, the largest increase since September 2022, suggesting firmer price pressures in smaller segments despite a cooler headline.
-
Core goods 3Mo3M annualized growth slowed to +0.4% (from around +2.5% in Q3 2025), indicating limited evidence of tariff-related inflation pressures in imported goods categories.