
AAR Rail Industry Overview: December 2025
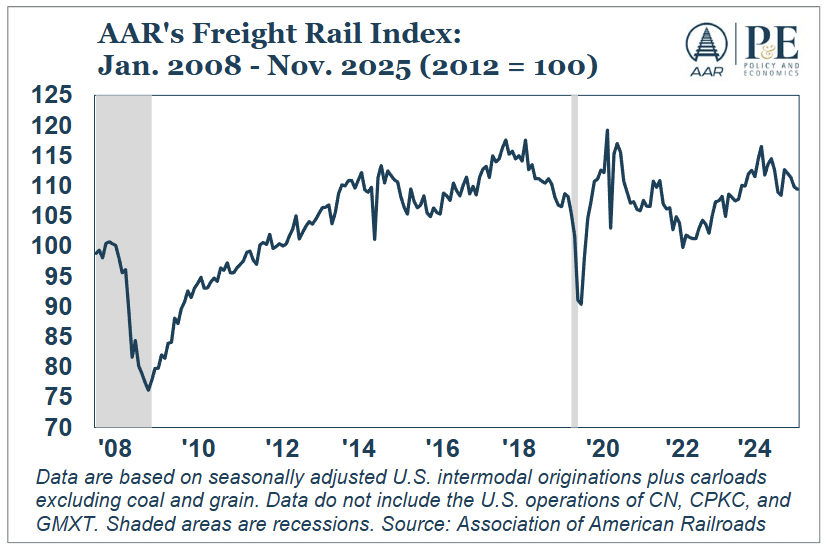
The AAR Freight Rail Index fell -0.4% MoM in November 2025 and was down -4.4% YoY, marking its seventh decline in eight months and underscoring weaker underlying freight demand driven largely by intermodal softness.
-
Grain carloads averaged 24,204 per week (+8.4% YoY), the highest since May 2021; year-to-date volumes were up 5.4%, supported by strong exports tied to competitive pricing and high crop quality.
-
Coal carloads averaged 58,382 per week (+3.1% YoY), their seventh increase in nine months, though November remained near historic lows; year-to-date volumes were +3.5%, helped by higher coal-fired electricity generation.
-
Carloads excluding coal rose 0.9% YoY, their eighth increase in nine months and the 20th in 22 months, with year-to-date volumes +1.3%, consistent with modest economic growth.
-
Chemical carloads fell -1.4% YoY, the third decline in six months, and averaged their lowest weekly level of 2025; however, year-to-date volumes were a record +1.3%, reflecting earlier strength before rising natural gas prices weighed on output.
-
Primary metal products declined -1.4% YoY, their first drop in nine months; despite the monthly pullback, year-to-date shipments were +3.4%, broadly in line with steel industry data.
-
Iron and steel scrap increased +11.1% YoY, the ninth straight rise, with year-to-date volumes +10.0%, the highest since 2011.
-
The industrial products category was essentially flat (-0.02% YoY), as gains in crushed stone and sand offset declines in autos, ores, and chemicals; the small change aligns with a generally sluggish manufacturing environment in 2025.