
CBI Industrial Trends Survey: October 2025
The survey, based on the responses of 218 manufacturing firms, found:
- Business sentiment deteriorated in October, with manufacturers’ optimism about both the business situation (weighted balance of -31%) and export prospects (-43%) declining further.
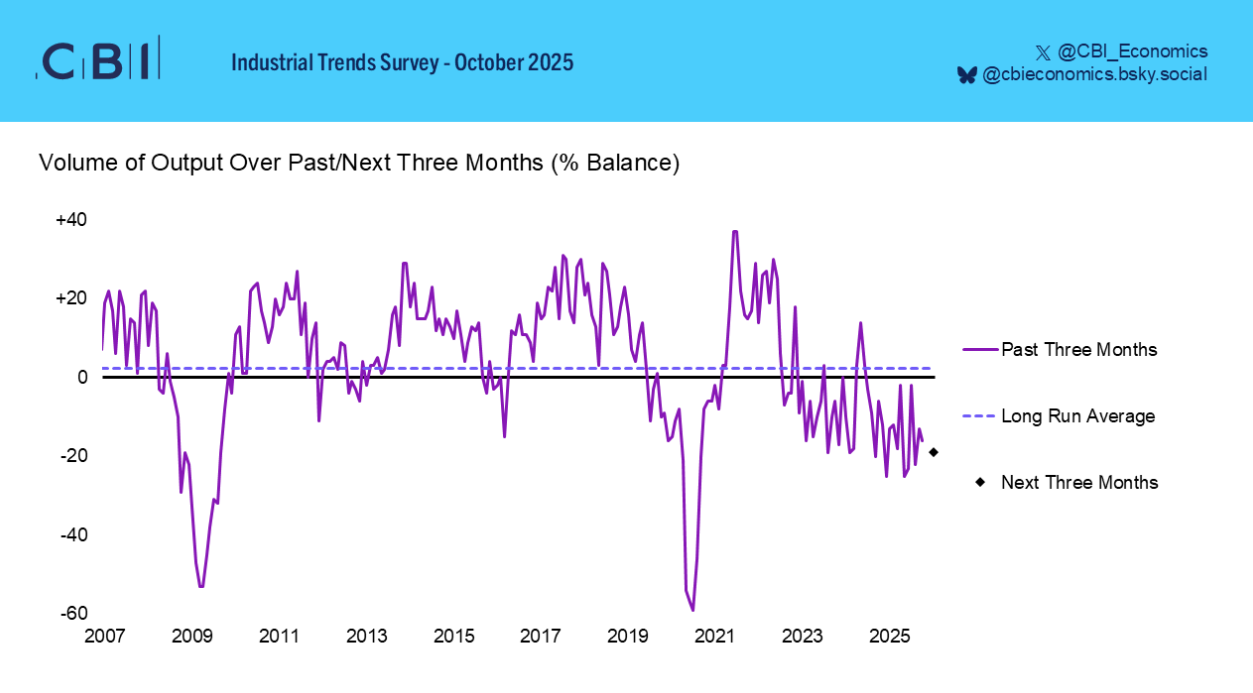
- Output volumes fell in the quarter to October, at a similar pace to the quarter to September (-16%, from -13% in the three months to September). Firms expect volumes to fall again in the three months to January (-19%).
- The decline in output volumes was broad-based (14 out of 17 sub-sectors) and was driven by declines in the metal products, metal manufacture, and electronic engineering sub-sectors.
- The share of firms citing orders or sales as a factor likely to limit output in the next three months rose from July and stands above the long-run average (73%, from 62% in July).
- Total new orders fell through the quarter (-20%, from -17% in July), reflecting the fastest pace of decline since July 2020 for both domestic orders (-26%) and export orders (-26%). Manufacturers expect the total volume of new orders to decline again in the three months to January (-23%).
- Investment intentions for the year ahead have deteriorated. Manufacturers expect to reduce investment in plant & machinery (-46%, the lowest since April 2020, from -15% in July), in buildings (-42%, from -28%), in product & process innovation (-20%, from -6%), and in training & retraining (-19%, from -13%).
- The share of firms citing capacity expansion as a reason for capital expenditure over the next 12 months fell to its lowest since April 2009 (13%, from 28% in July). 47% of respondents cited increased efficiency as a reason for capex, and 46% cited replacement.
- The main constraint on investment was uncertainty about demand (cited by 65% of manufacturers, the greatest proportion since January 2021), followed by inadequate net return (35%), and a shortage of internal finance (20%).
- Average costs rose in the quarter to October at an elevated pace (+52%, from +63% in July; long-run average of +19%). Costs growth is expected to remain elevated in the quarter to January (+52%).
- Average domestic prices rose, but at a slower pace relative to July (+12%, from +33% in July), whereas export prices fell (-8%). Both domestic and export prices are anticipated to rise in the next three months (+16% and +8%, respectively).
- Stocks of work in progress fell in the three months to October (-10%), accompanied by a fall in stocks of finished goods (-8%, the fastest pace of decline in five years). Stocks of raw materials were broadly flat (-1%).
- Manufacturers expect stocks of finished goods (-23%, the weakest expectations since January 2021), of raw materials (-19%) and of work in progress (-14%) to all fall in the three months to January.
- Numbers employed fell in the quarter to October (-18%, from -11% in July) at the fastest pace in five years. Manufacturers expect another fall in employment in the quarter to January (-16%).
- Manufacturing competitiveness deteriorated across all major markets in the three months to October. Competitiveness in non-EU markets worsened at a slightly slower pace (-19%, from -23% in July), whereas competitiveness in EU (-18%, from -13%) and UK (-15%, from -4%) markets weakened further.
- Competitiveness is expected to decline again in the three months to January, particularly in UK markets (-23%, the weakest expectations since April 2020), followed by EU (-18%) and non-EU (-18%, a record low) markets.