


Texas Service Sector Outlook Survey: September 2025
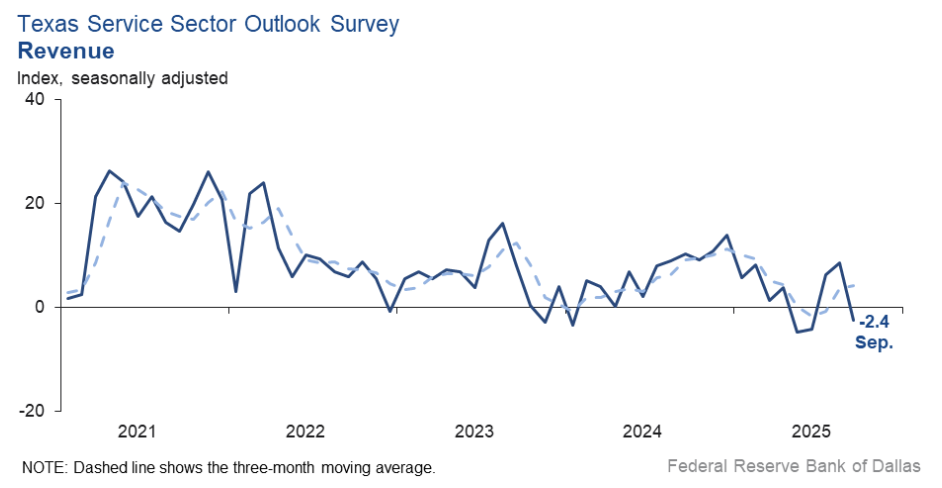
The Texas Service Sector Revenue Index fell -11.0 pts to -2.4 in September 2025, marking a shift back into contraction as broader activity and outlook measures weakened.
-
Employment declined to -3.6 (from 1.2), pointing to job losses, while part-time employment improved modestly to -0.6 (from -2.7).
-
Hours worked slipped -6.1 pts to -1.0, signaling little change in workweeks overall.
-
General business activity dropped -12.4 pts to -5.6, and the company outlook index fell -6.9 pts to -2.6, both reflecting weaker sentiment.
-
Outlook uncertainty rose sharply to 22.5 (from 11.2), indicating greater concern among firms.
-
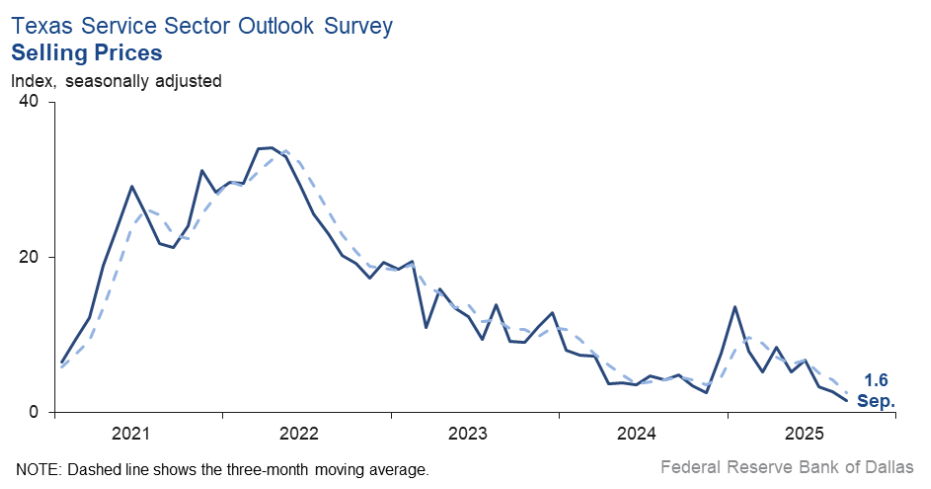
Input prices eased to 24.4 (from 27.9), and wages & benefits moderated to 11.9 (from 15.7), while selling prices held steady at 1.6.
-
Capital expenditures improved slightly to 7.3 (from 5.8), remaining in positive territory.
-
Future expectations stayed more optimistic, with the future revenue index at 35.3 and the future general business activity index at 11.6, suggesting firms anticipate growth in the next six months.
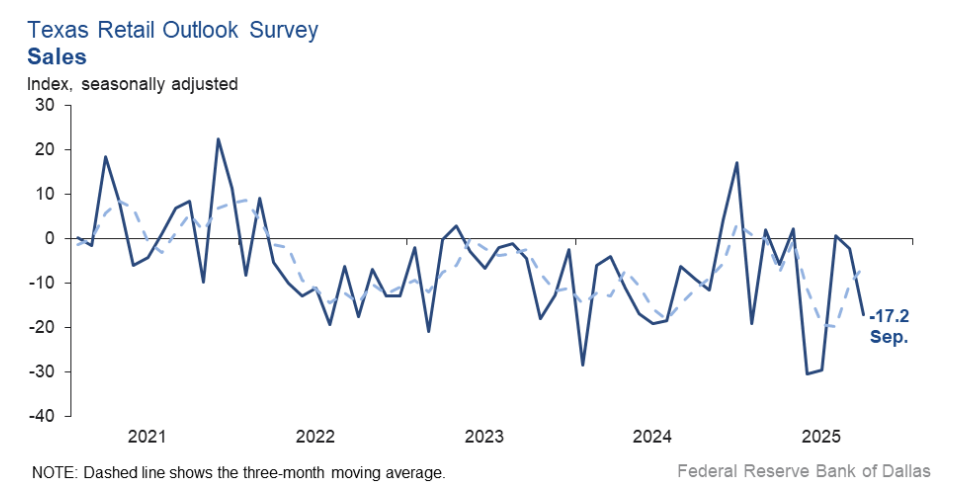
The Texas Retail Sales Index fell -15.1 pts to -17.2 in September 2025, signaling a sharper contraction in statewide retail activity as business sentiment and outlook weakened further.
-
Employment declined to -3.0 (from -2.0), while part-time employment improved to -3.9 (from -15.5), and hours worked slipped further to -8.2 (from -3.6), indicating softer labor demand.
-
General business activity dropped -16.6 pts to -14.7, and the company outlook index fell -6.1 pts to -5.4, both reflecting deteriorating sentiment.
-
Outlook uncertainty rose sharply to 26.6 (from 8.2), highlighting elevated concern among retailers.
-
Input prices were stable at 22.0, while selling prices increased to 9.2 (from 4.1), and wages & benefits held steady at 12.6, pointing to steady but persistent cost pressures.
-
Capital expenditures rose to 13.7 (from -0.1), signaling firmer investment activity despite weaker sales.
-
Companywide sales remained weak at -8.2, though companywide internet sales improved to -1.9 (from -10.0).
-
Future expectations softened, with the future sales index at 26.6 (down from 29.6), while future general business activity eased to 4.7 (from 13.8), suggesting slower but still positive growth ahead.