
Logistics Managers’ Index: August 2025
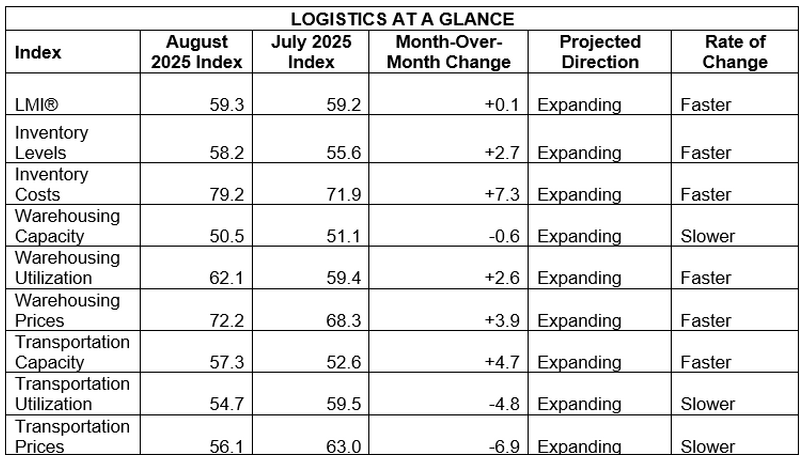
The Logistics Managers’ Index (LMI) rose to 59.3 in August 2025 (+0.1 MoM; +2.8 YoY), indicating moderate expansion with mixed sub-components and a mild negative freight inversion.
-
Inventory Levels: 58.2 (+2.7 pts MoM) indicating a broad-based stock build, with Upstream 58.1 and Downstream 57.1 converging as inventories move toward retail.
-
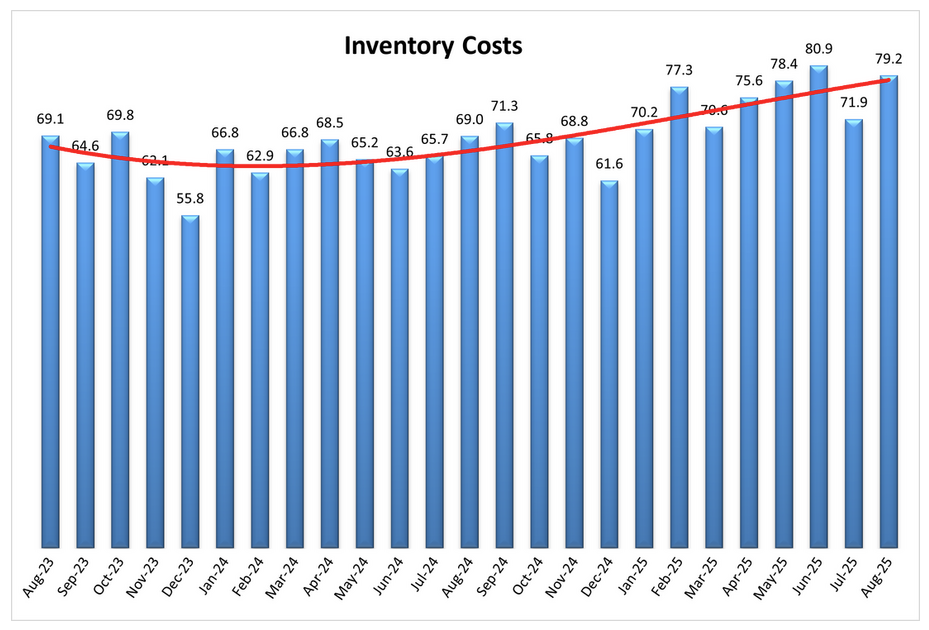
Inventory Costs: 79.2 (+7.3) rising near two-year highs; both small (83.7) and large firms (72.2) report strong cost expansion, implying pressure on margins.
-
Warehousing: Capacity 50.5 (-0.6) and Utilization 62.1 (+2.6), Prices 72.2 (+3.9) pointing to tighter storage conditions, especially later in the month when capacity dipped into mild contraction (~49.1).
-
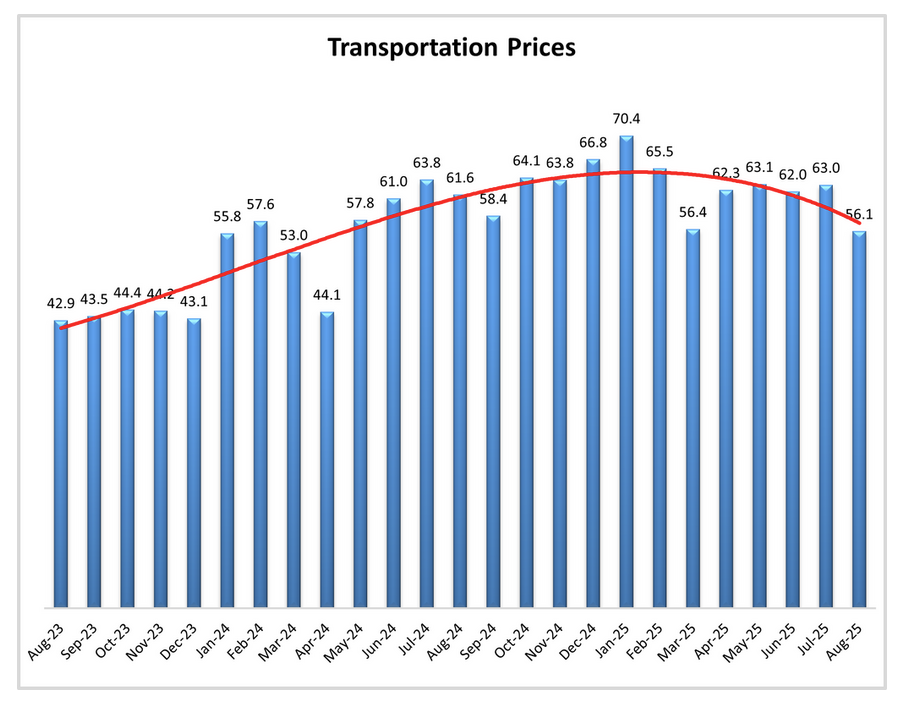
Transportation: Prices 56.1 (-6.9) and Utilization 54.7 (-4.8) while Capacity 57.3 (+4.7). Capacity now expanding faster than Prices (≈1.2-pt gap), signaling a slight negative freight inversion and softer upstream pricing (Upstream 51.5 vs Downstream 66.1).
-
Firm size split: Overall index higher for smaller firms at 62.7 vs 58.2 for larger firms, driven by higher inventory costs and tighter storage for small firms.
-
Timing effects: Early-month Transportation Utilization ~61.5 fell to ~50.0 late in August; Warehousing Capacity shifted from mild expansion (~52.8) to mild contraction (~49.1), indicating late-month slack in freight but tighter storage.
-
August reading is just below the long-run LMI average (61.5), pointing to steady, but not overheated, logistics activity.