


S&P Global Manufacturing PMIs: May 2025
Global - 6/3/2025
Asia Pacific
- Australia - 6/1/2025
- Malaysia - 6/3/2025
- ASEAN - 6/4/2025
- Myanmar - 6/2/2025
- Philippines - 6/2/2025
- Thailand - 6/4/2025
- Vietnam - 6/2/2025
- Indonesia - 6/2/2025
- Japan - 6/2/2025
- Taiwan - 6/2/2025
- China - 6/3/2025
- India - 6/2/2025
- Russia - 6/2/2025
- Kazakhstan - 6/2/2025
- South Korea - 6/2/2025
- Pakistan - 6/2/2025
Europe
- Austria - 5/27/2025
- Ireland - 6/3/2025
- Netherlands - 6/2/2025
- Romania - 6/2/2025
- Turkiye - 6/2/2025
- Poland - 6/2/2025
- Spain - 6/2/2025
- Czechia - 6/2/2025
- Italy - 6/2/2025
- France - 6/2/2025
- Germany - 6/2/2025
- Eurozone - 6/2/2025
- Greece - 6/2/2025
- UK - 6/2/2025
North & South America
Key Results
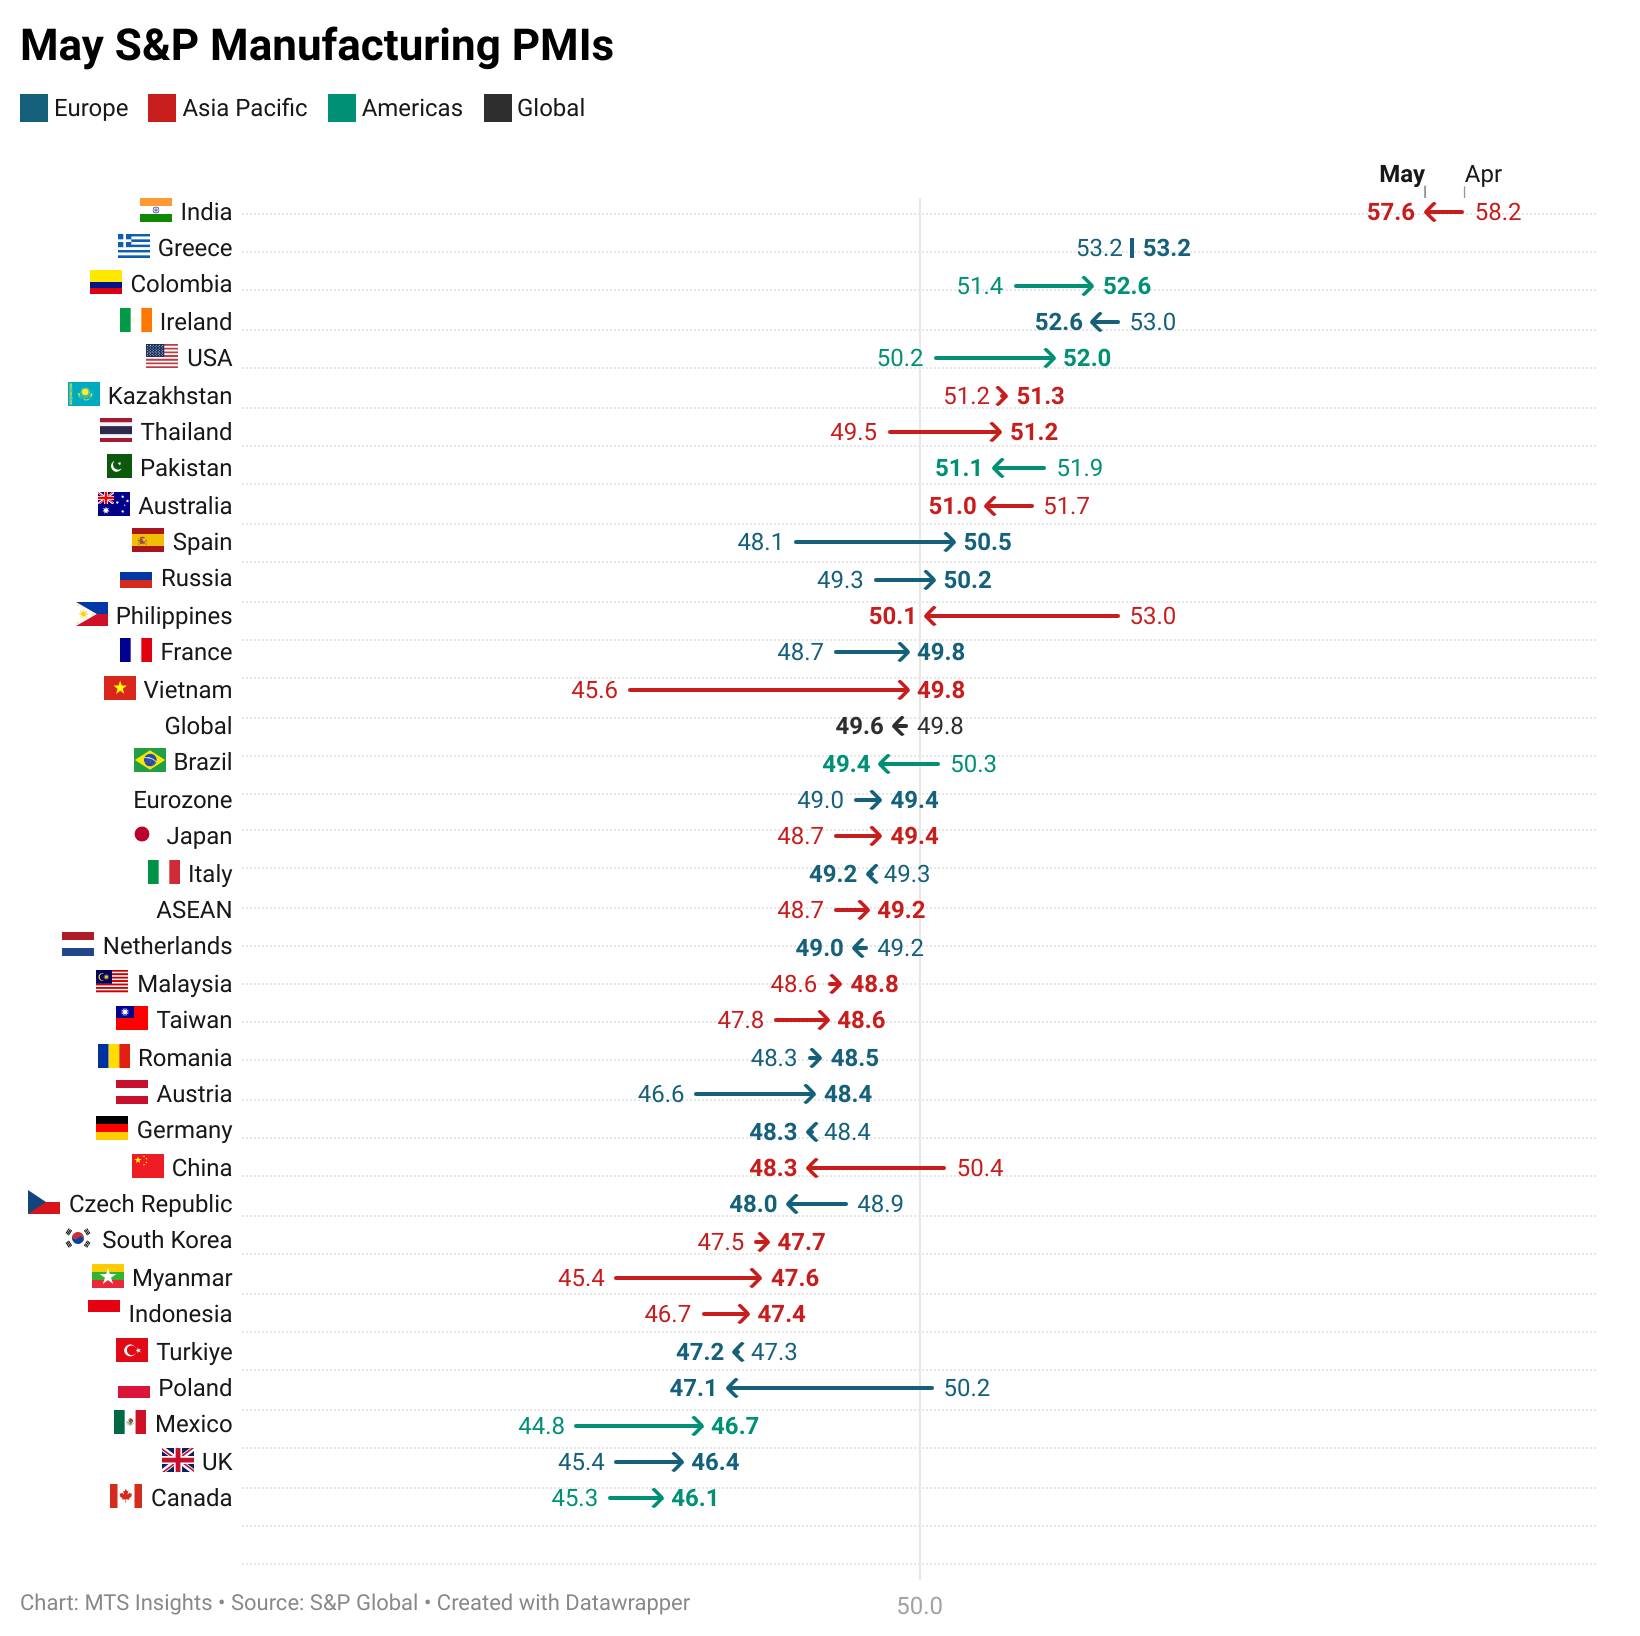
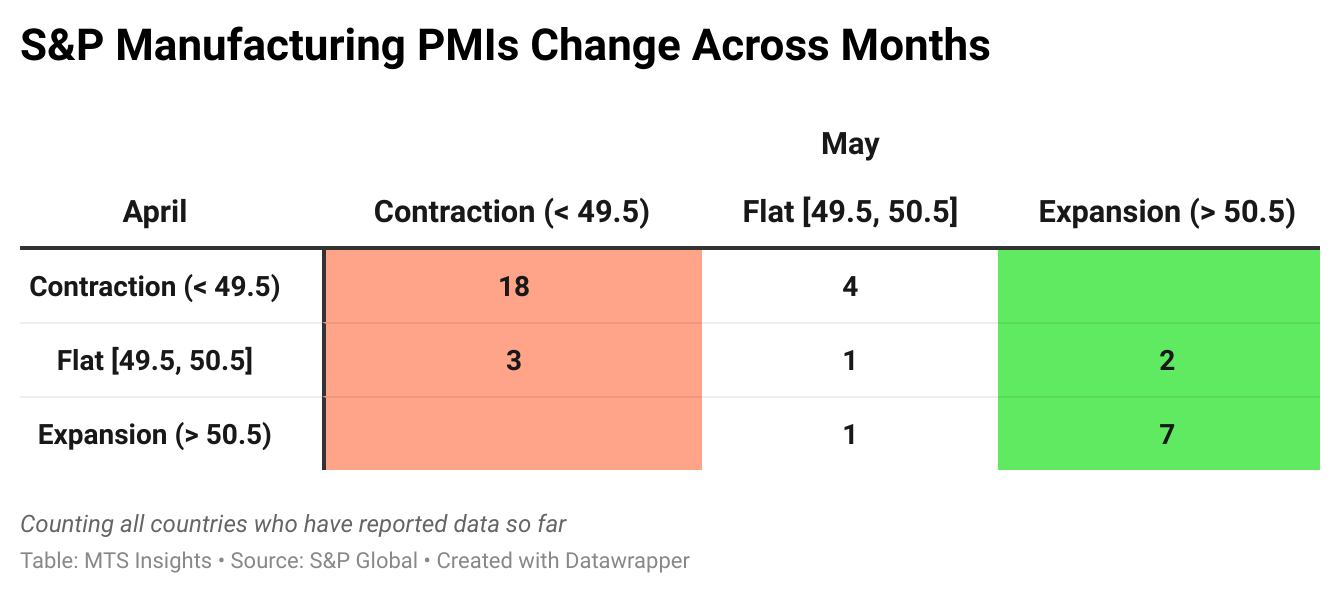
South Korea
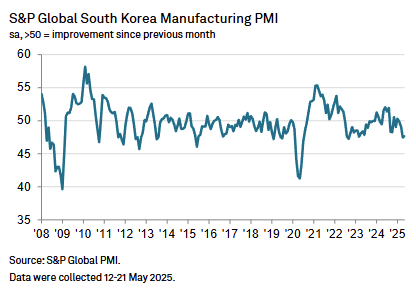
South Korea’s S&P Manufacturing PMI remained weak in May, improving only 0.2 pts to 47.5.
- While the headline index saw a slight improvement, the decline in new orders fell to the steepest since June 2020, and output declined at the sharpest rate in 31 months.
- Despite that, employment was the strongest since September 2023, and confidence improved on hopes that trade tensions would be resolved.
Japan
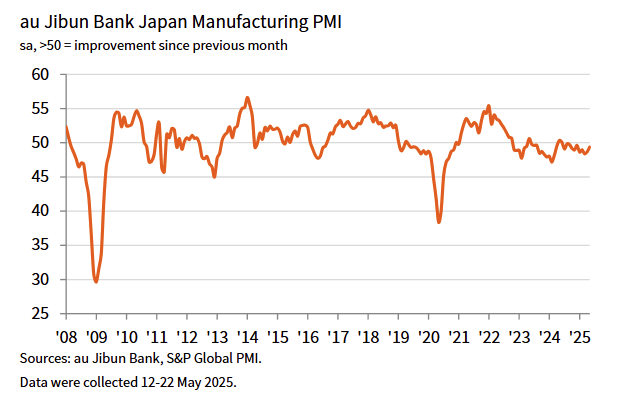
Japanese manufacturing conditions improved to the best so far in 2025 as its S&P Manufacturing PMI increased 0.7 pts to 49.4 in May, ahead of expectations of a smaller rise to 49.0.
China
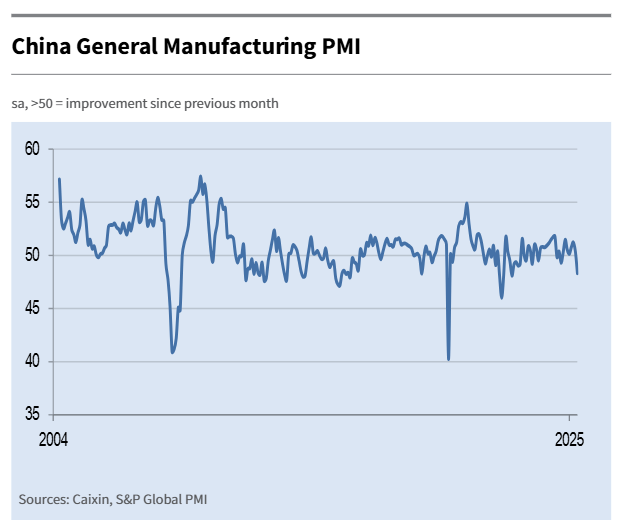
China’s S&P Manufacturing PMI fell -2.1 pts to 50.4 in May, the lowest since September 2022 and the first contraction since September 2024.
- Manufacturing output fell for the first time in 19 months as new orders contracted at the sharpest pace in about 2.5 years.
- Average input costs and output charges continued to decline midway through the second quarter of 2025.
- Despite weak conditions, sentiment became more optimistic on hopes that trade conditions would improve
Eurozone
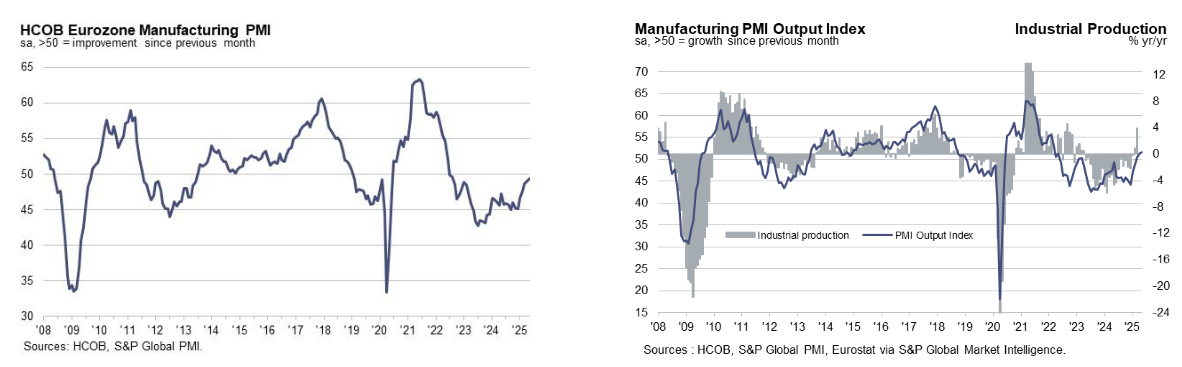
The S&P Eurozone Manufacturing PMI reached its highest in 33 months in May, up 0.4 pts to 49.4.
- France and Austria were the major drivers of the new high as their PMIs increased to 28-month and 32-month highs, respectively.
- Output growth (though it was only slight) was the joint-fastest since March 2022.
- Despite that, backlogs fell at the weakest rate since June 2022, and employment still declined (but at the weakest rate since September 2023).
- The level of positive sentiment rose to its highest since February 2022 and was above its long-term average.
US
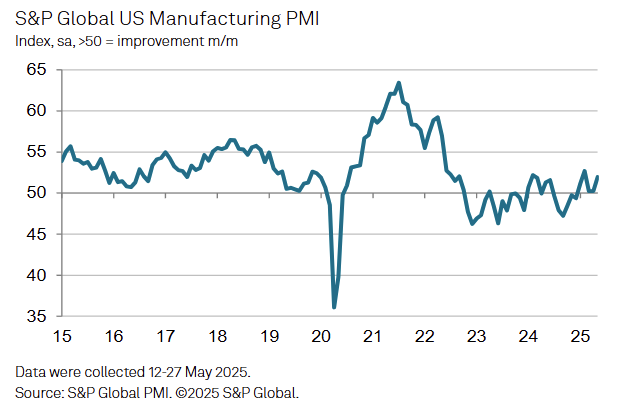
The S&P US Manufacturing PMI increased 1.8 pts to 52.0 in May, mostly in line with expectations and the best since February.
- The outlook improved to a 3-month high on hopes that trade policy would stabilize.
- Growth was driven partly by a record increase in input inventories. New order growth was low, but still the strongest in the last three months.
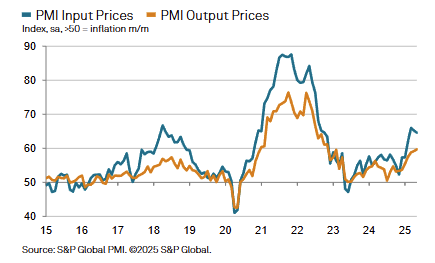
- Raw material price inflation remained high and drove selling price inflation to the highest since November 2022.