
Cox Automotive EV Market Monitor: April 2025
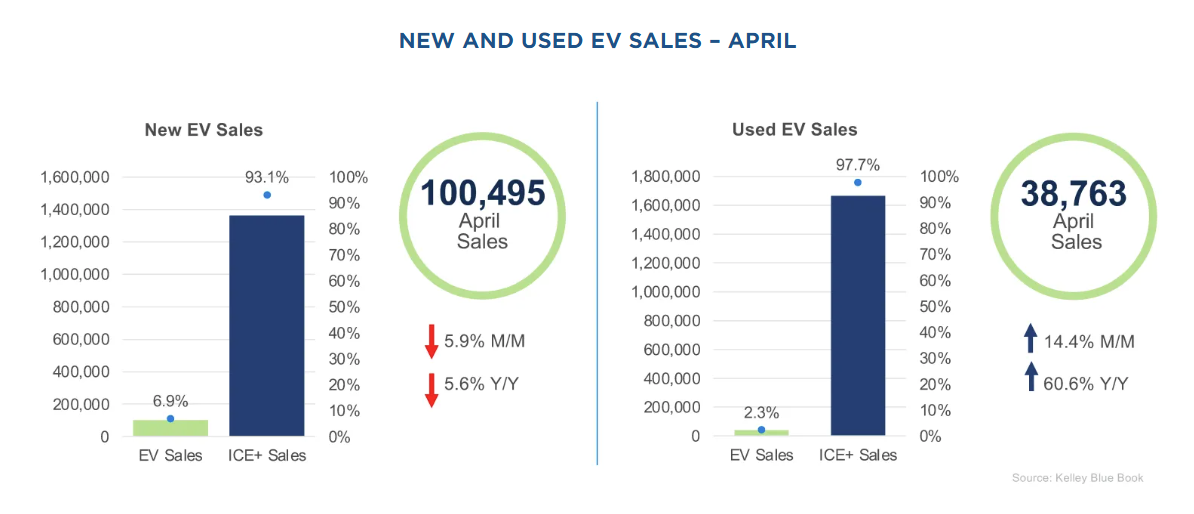
The new EV market faced several challenges in April, reflecting broader economic trends. The volume of new EV sales declined by 5.9% month over month to 100,495 units, while the EV market share rose slightly to 6.9%. Year over year, the EV sales volume decreased by 5.6%.
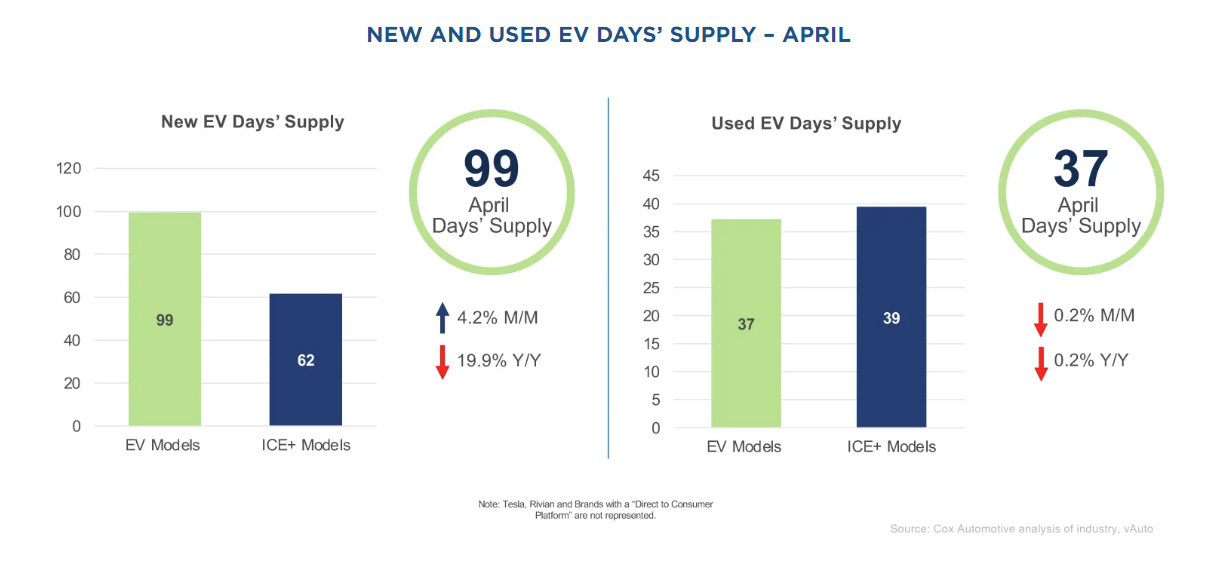
In April, the new EV days’ supply increased by six days, up 4.2%, month over month, rising to 99 days. Year over year, the new EV days’ supply is down nearly nine days (19.9%), marking the widest gap between EV and ICE+ days’ supply since July 2024. In April, the days’ supply of used electric vehicles declined by 0.2% month over month and year over year.
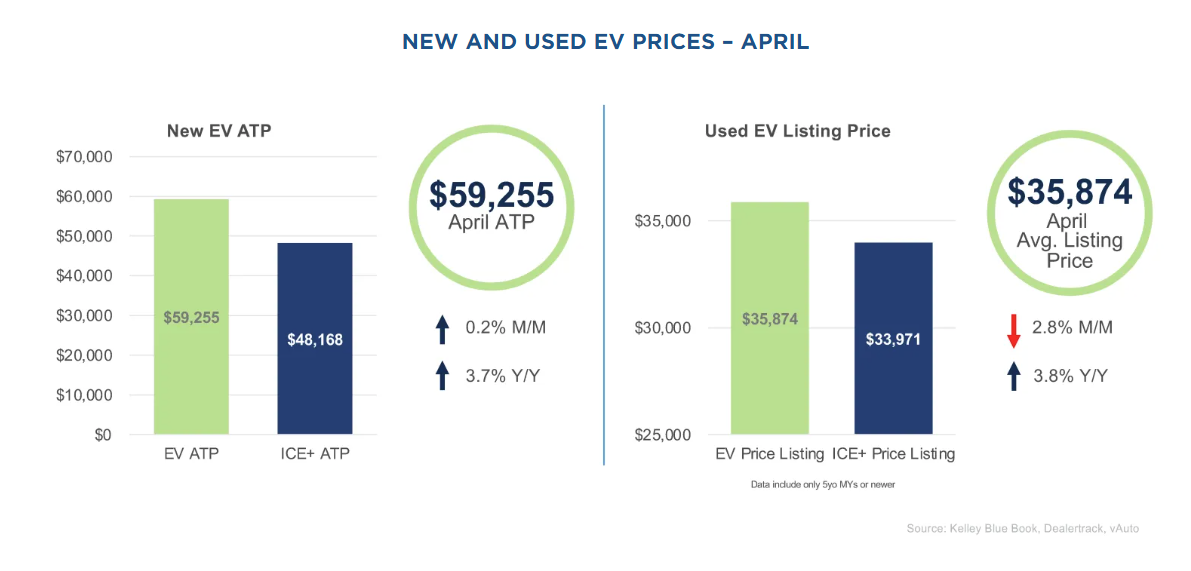
In April, the average transaction price (ATP) for new electric vehicles was $59,255, showing a 0.2% increase from the previous month and a 3.7% increase from the previous year. The price difference between EVs and ICE+ dropped to $11,087, driven by a 2.6% month-over-month increase in ICE+ ATP. Tesla’s ATP increased by 2.6% month over month to $56,120, the highest this year. EV incentives declined by 14% to $6,886, which is 11.6% of the ATP and the lowest dollar amount since June 2024. Despite this decline, EV incentives are still more than double the ICE+ average.
In April 2025, the average listing price for used electric vehicles (EVs) was $35,874, showing a 2.8% decline from the previous month but a 3.8% increase compared to the same period last year. The price gap between used EVs and internal combustion engine (ICE) vehicles moved below $2,000, the lowest it’s been since July 2024.