

Paychex Small Business Employment Watch: April 2026
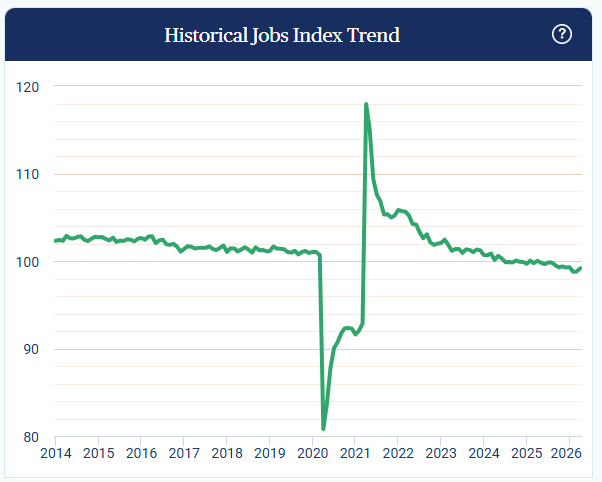
The Paychex Small Business Jobs Index rose +0.35 pts MoM to 99.16 in April 2026 but remained -0.86 pts YoY lower, marking the strongest monthly gain in over a year while still below the 100 baseline.
- The national index increased to 99.16 (+0.35 pts MoM), representing the largest one-month gain in over a year and contributing to the largest two-month increase (+0.39 pts) since February 2023.
- On a YoY basis, the index declined from 100.02 to 99.16 (-0.86 pts YoY), indicating that small business employment growth remains slower than a year earlier despite recent improvement.
- The Midwest remained the top-performing region for the 23rd consecutive month at 99.55, while all regions posted MoM gains, led by the Northeast (+0.56 pts) and West (+0.50 pts), showing broad-based strengthening.
- The Northeast reached 99.45 and was the only region to improve over the past quarter (+0.17 pts since January), indicating more sustained regional momentum compared with others.
- The West remained the weakest region at 98.55 despite its monthly gain, highlighting continued relative underperformance even as conditions improved.
- At the state level, Wisconsin led at 100.84 (+0.42 pts), while Pennsylvania (100.48), North Carolina (100.07), and Washington (100.05) all moved above 100, with Washington rebounding +3.47 pts from the prior month.
- Education and Health Services led sectors at 100.49, while Construction posted the largest MoM gain (+0.64 pts to 98.97); Manufacturing (98.20) remained among the weakest sectors, continuing a prolonged period of underperformance.
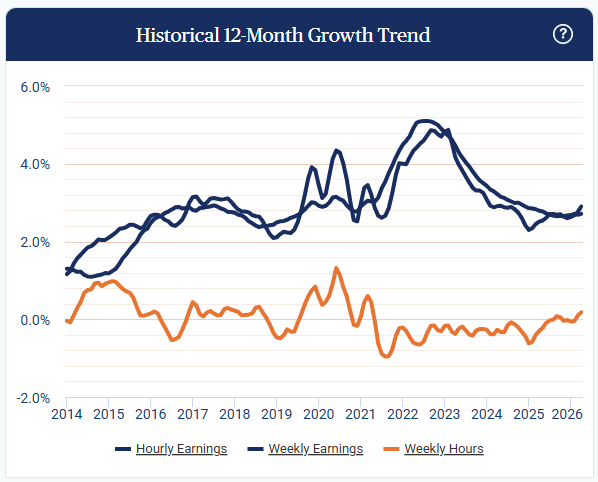
Hourly earnings growth held at +2.71% YoY in April 2026 while weekly earnings rose +2.90% YoY and weekly hours worked increased +0.18% YoY, indicating steady wage gains alongside improving labor utilization.
- Hourly earnings growth remained at +2.71% YoY, staying below 3% for the 18th consecutive month, indicating a prolonged period of moderate wage growth.
- Three-month annualized hourly earnings growth was +2.83%, remaining below 3% for nearly two years, reinforcing the stability of underlying wage trends.
- Weekly earnings growth rose to +2.90% YoY, its highest level since May 2024, with one-month and three-month annualized growth above 4%, pointing to stronger short-term momentum.
- Weekly hours worked increased +0.18% YoY, marking a second consecutive positive reading, a pattern seen only twice in the past five years, suggesting improving labor utilization.
- Regionally, the Northeast led hourly earnings growth at +3.01% YoY, while the South lagged at +2.51% YoY for the 11th straight month, indicating persistent regional divergence.
- The West led weekly hours worked growth at +0.55% YoY, with one-month annualized gains above 1% throughout 2026, highlighting relatively stronger labor utilization trends.
- At the state level, Indiana led with +4.37% YoY hourly earnings growth and +4.47% YoY weekly earnings growth, while Georgia remained the weakest at +2.10% YoY despite a recent uptick.
- By sector, Other Services led hourly earnings growth at +3.16% YoY, Construction recorded the strongest weekly earnings (+3.41%) and hours worked (+0.49%), while Education and Health Services lagged at +2.15% YoY and sectors such as Leisure and Hospitality (-0.24%) saw declines in weekly hours worked.
Attachments
1