


US PPI: September 2025 (DELAYED)
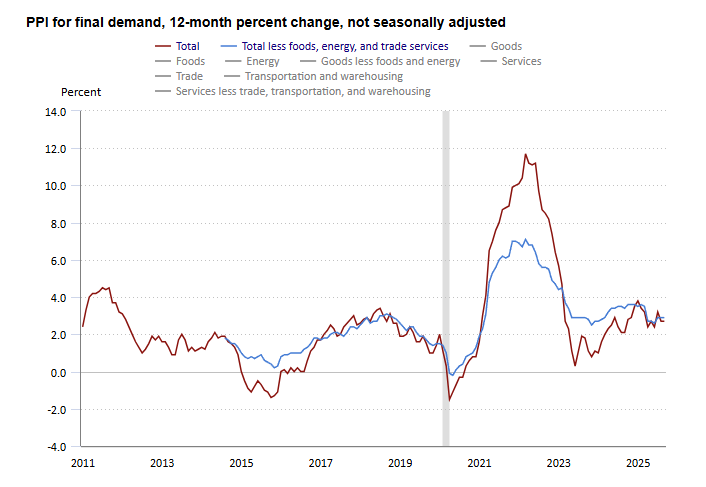
U.S. producer prices rose 0.3% MoM in September (+2.7% YoY), marking a rebound from August’s decline and reflecting firmer goods inflation while services remained flat.
-
Final demand goods increased 0.9% MoM, driven mainly by a sharp +11.8% jump in gasoline, with additional support from higher prices for meats, ethanol, natural gas liquids, and structural metal products. This marked the third straight monthly increase in goods prices.
-
Final demand services were unchanged MoM, as a -0.8% decline in trade services margins offset increases in transportation and warehousing (+0.4% MoM). The flat reading follows two months of firmer services inflation.
-
Core PPI (less foods, energy, and trade) edged up 0.1% MoM (+2.9% YoY), easing from August’s +0.3% rise but maintaining a moderate upward trend.
-
Processed goods for intermediate demand rose 0.4% MoM (+3.8% YoY), supported by higher processed energy goods (+0.9% MoM) and processed foods (+1.1% MoM), indicating continued pipeline cost pressure.
-
Unprocessed intermediate goods increased 0.1% MoM, as food/feedstuffs jumped +1.9% and nonfood materials rose +1.5%, while unprocessed energy fell -3.0% MoM, led by natural gas (-8.7% MoM).
-
Intermediate demand services increased 0.1% MoM, with food wholesaling margins up +3.8% MoM accounting for most of the gain; loan services fell -3.4%.
-
Across production stages, intermediate demand inflation remained firm, with Stage 4 (+0.2% MoM), Stage 3 (+0.3% MoM), and Stage 1 (+0.4% MoM) all rising, while Stage 2 edged down (-0.1% MoM), showing broad but varied cost pressures across supply chains.