

Investment Manager Index: October 2025
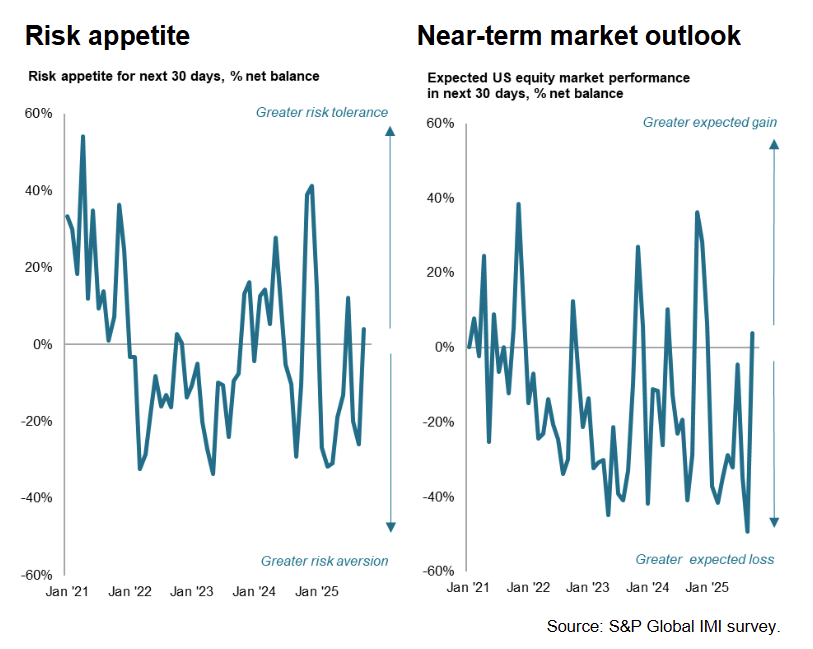
The S&P Global Investment Manager Index (IMI) Risk Appetite Index rebounded to +4% in October from -26% in September, reflecting renewed investor optimism following the Federal Reserve’s first rate cut of the year.
-
The rate cut drove a broad improvement in sentiment, though optimism remains well below levels seen early in 2025 amid lingering concerns over valuations and political uncertainty.
-
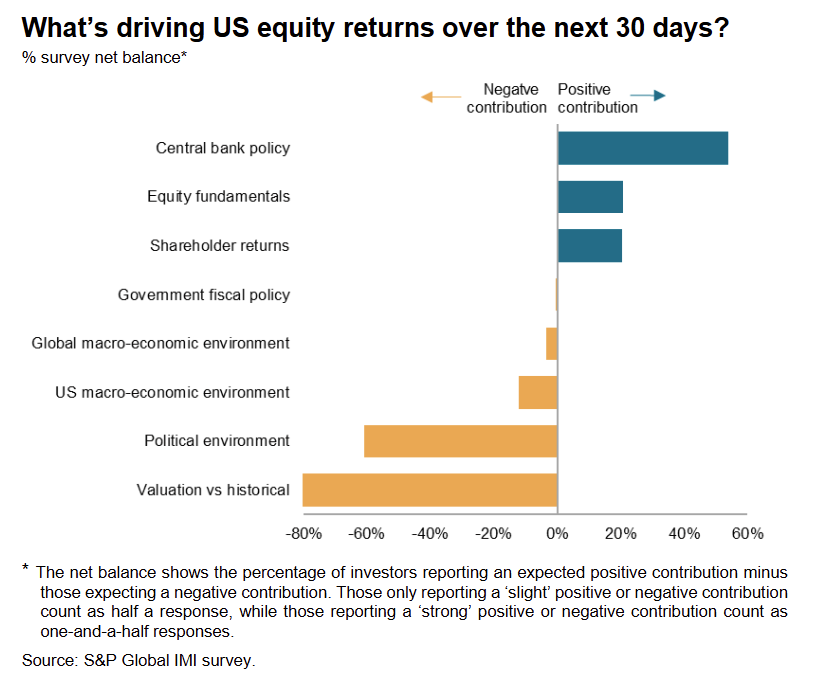
Equity fundamentals were viewed more favorably, with U.S. macroeconomic conditions exerting the smallest perceived drag since February.
-
Sector sentiment shifted toward cyclicals, with technology stocks seeing the sharpest rebound, now the second-most favored sector behind financials, while materials, communication services, and industrials also improved.
-
Bearishness in consumer discretionary moderated, while sentiment turned more negative for real estate and weakened sharply for consumer staples.
-
Globally, equities became the most favored asset class since April 2021, followed by commodities, which saw their most bullish sentiment since April 2022.
-
Regionally, Japanese and Chinese equities led investor preference for expected year-end performance, while the UK and Latin America ranked lowest.
-
Fiscal policy was no longer viewed as a drag for the first time in nine months, and easing Middle East tensions reduced geopolitical risk, though Russia remained a top concern.