
Logistics Managers’ Index: February 2025
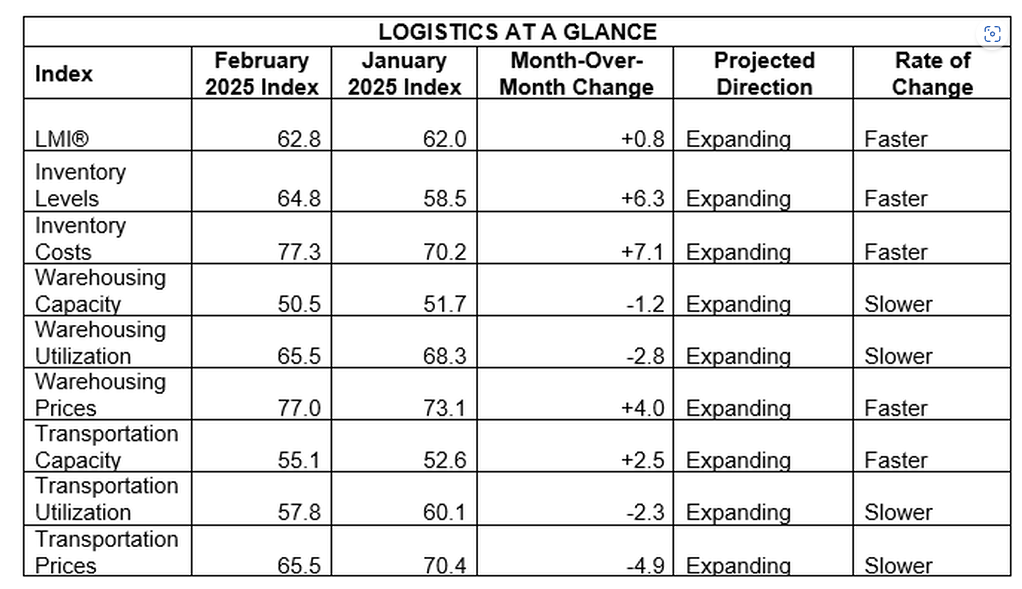
The Logistics Managers’ Index increased 0.8 pts to 62.8 in February, the highest since June 2022, driven by inventory buildup and warehousing strain.
- The Inventory Levels and Inventory Costs indexes increased the most, up 6.3 pts to 64.8 and up 7.1 pts to 77.3 (the highest since February 2022) respectively.
- As inventory growth surged, Warehousing Capacity growth eased further, down -1.2 pts to 50.5, indicating almost no growth in capacity.
- Warehousing Prices hit 77.0, up 4.0 pts, with late-February rates skyrocketing to 85.6 due to static inventories.
- There is evidence companies are abandoning lean inventory practices for just-in-case (JIC) stockpiling, mirroring 2021–2022 inflationary trends, ahead of tariffs.
- Transportation Capacity expanded 2.5 pts to 55.1, but Utilization slowed to -2.3 pts to 57.8, suggesting stagnant inventory movement post-tariff rush.
- Transportation Prices eased -4.9 pts to 65.5, though still elevated, indicating sustained demand but loosening market conditions.
- Survey respondents see a rise in costs across inventories, warehousing, and transportation in the future.