
 USA
/
Institute of Supply Management
ISM Services PMI
About
-
December 3rd, 2026 · 10:00 AM
-
January 6th, 2027 · 10:00 AM
-
February 3rd, 2027 · 10:00 AM
-
March 3rd, 2027 · 10:00 AM
-
April 5th, 2027 · 10:00 AM
-
May 5th, 2027 · 10:00 AM
-
June 3rd, 2027 · 10:00 AM
-
July 6th, 2027 · 10:00 AM
-
August 4th, 2027 · 10:00 AM
-
September 3rd, 2027 · 10:00 AM
-
October 5th, 2027 · 10:00 AM
Charts & Data
Latest Releases
12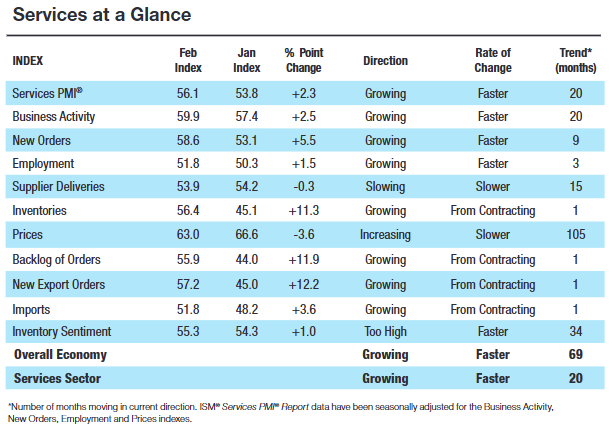
The ISM Services PMI rose to 56.1 in February 2026 (+2.3 pts MoM), the strongest reading since July 2022 and well above the 12-month average of 52.0, signaling faster expansion in U.S. services activity.
-
The Business Activity Index increased to 59.9 (+2.5 pts MoM), marking one of the strongest readings since late 2022 and indicating a faster pace of services output growth across industries.
-
The New Orders Index climbed to 58.6 (+5.5 pts MoM), remaining firmly in expansion territory and highlighting stronger incoming demand for services.
-
The Employment Index rose to 51.8 (+1.5 pts MoM), marking the third consecutive month of expansion and suggesting services sector hiring activity continued to improve modestly.
-
The Supplier Deliveries Index eased slightly to 53.9 (-0.3 pts MoM) but remained above 50 for a 15th straight month, indicating deliveries continued to slow as demand remained solid.
-
The Prices Index declined to 63.0 (-3.6 pts MoM), its lowest reading since March 2025, though it remained above 60 for a 15th consecutive month, pointing to still-elevated cost pressures despite some easing.
-
The Inventories Index jumped to 56.4 (+11.3 pts MoM) from contraction in January, indicating inventory levels increased as firms prepared for expected activity in the coming quarters.
-
The Backlog of Orders Index rose sharply to 55.9 (+11.9 pts MoM), moving back into expansion for the first time since February 2025 and reflecting a buildup in outstanding work.
-
The New Export Orders Index rebounded to 57.2 (+12.2 pts MoM) and the Imports Index returned to expansion at 51.8 (+3.6 pts MoM), signaling renewed growth in cross-border services demand and input sourcing.
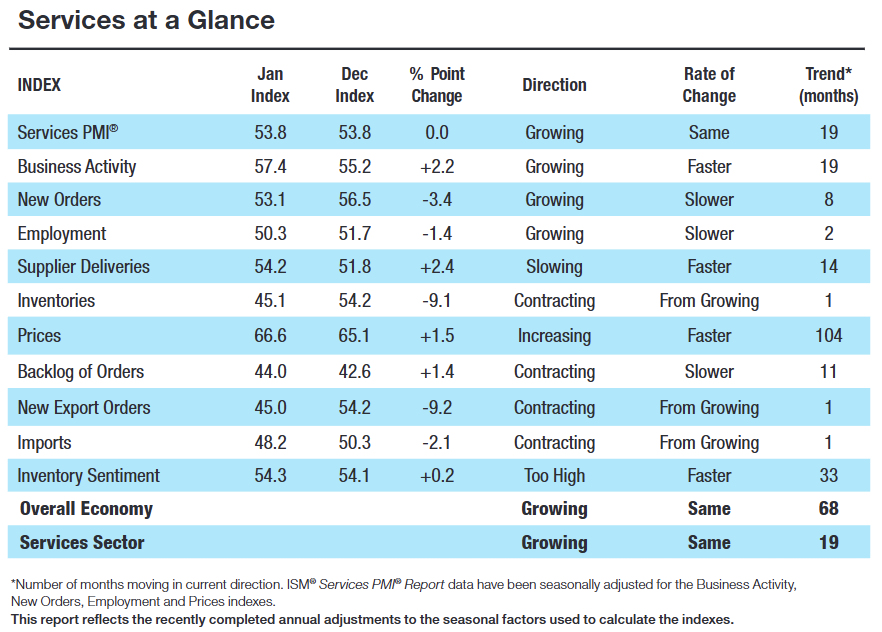
The ISM Services PMI held at 53.8 in January 2026 (unchanged from December), marking a 19th consecutive month in expansion and running about +2.0 pts above the 12-month average (51.8).
-
The Business Activity Index rose to 57.4 (+2.2 pts MoM), the highest since October 2024, signaling faster services output growth.
-
The New Orders Index fell to 53.1 (-3.4 pts MoM) but stayed in expansion, indicating slower demand growth even as orders continued to rise.
-
The Employment Index eased to 50.3 (-1.4 pts MoM) but remained barely expansionary for a second month, suggesting hiring continued but at a slower pace.
-
The Supplier Deliveries Index increased to 54.2 (+2.4 pts MoM), indicating slower deliveries and the highest reading since October 2024.
-
The Prices Index climbed to 66.6 (+1.5 pts MoM) and remained above 60 for a 14th straight month, showing elevated cost pressures that moved higher again in January.
-
The Inventories Index dropped to 45.1 (-9.1 pts MoM), shifting back into contraction after two months of expansion, while Inventory Sentiment stayed in “too high” territory at 54.3 (+0.2 pts).
-
The Backlog of Orders Index rose to 44.0 (+1.4 pts MoM) but stayed in contraction for an 11th month, and New Export Orders fell to 45.0 (-9.2 pts) as exports moved back into contraction after one month of growth.
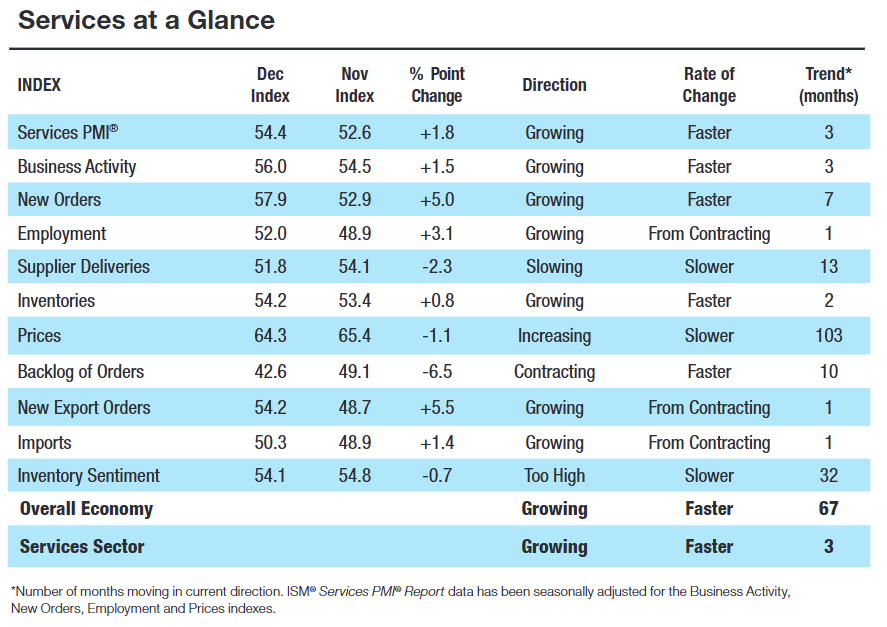
The ISM Services PMI rose +1.8 pts to 54.4 in December 2025 (from 52.6 in November), the highest reading since October, signaling faster services-sector expansion at year-end.
-
The Business Activity Index increased to 56.0 (+1.5 pts MoM), indicating a quicker pace of output growth and extending expansion to a third consecutive month.
-
The New Orders Index jumped to 57.9 (+5.0 pts MoM), its fastest growth in seven months, pointing to a notable acceleration in demand entering 2026.
-
The Employment Index moved back into expansion at 52.0 (+3.1 pts MoM) after six months in contraction, marking its first expansionary reading since May 2025.
-
The Supplier Deliveries Index eased to 51.8 (-2.3 pts MoM) but remained above 50 for a 13th straight month, indicating delivery times are still slowing, though at a reduced pace.
-
The Prices Index declined to 64.3 (-1.1 pts MoM), the lowest since March 2025, but stayed above 60 for a 13th consecutive month, showing cost pressures remain elevated despite some easing.
-
The Inventories Index rose to 54.2 (+0.8 pts MoM), signaling a second month of inventory expansion, while Inventory Sentiment stayed in “too high” territory at 54.1 (-0.7 pts).
-
The Backlog of Orders Index fell further into contraction at 42.6 (-6.5 pts MoM), extending the contraction streak to ten months and indicating faster clearing of outstanding work.
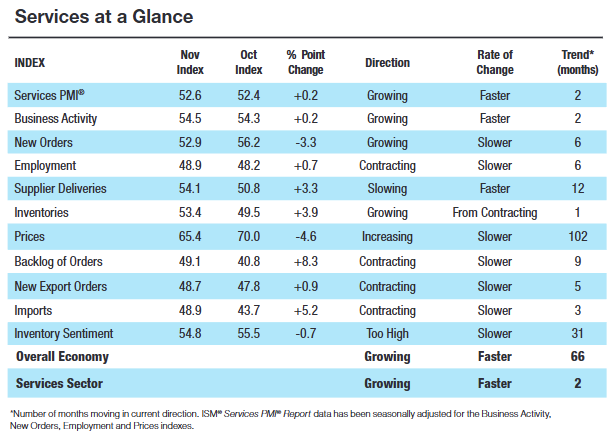
The ISM Services PMI rose +0.2 pts to 52.6 in November 2025 (from 52.4 in October), staying in expansion for a ninth month and sitting 0.9 pts above its 12-month average, indicating modest but ongoing services-sector growth.
-
Business Activity held firm at 54.5 in November (+0.2 pts), while the New Orders Index eased to 52.9 (-3.3 pts) but remained above its 12-month average of 51.7 and has now been in expansion in 33 of the last 35 months, showing demand is still growing but at a slower pace.
-
The Employment Index remained in contraction at 48.9 (+0.7 pts), marking a sixth straight month below 50 but its highest reading since May, with respondents noting both efforts to fill vacancies and difficulty attracting applicants under in-office requirements.
-
Supplier Deliveries rose to 54.1 (+3.3 pts), signaling slower delivery times for a 12th consecutive month and the second-highest reading since October 2022, as respondents cited tariffs, border delays tied to the government shutdown, and customs processing issues.
-
The Prices Index fell to 65.4 (-4.6 pts from 70.0), its lowest since April but still above 60 for the 12th straight month and marking the 102nd consecutive month of price increases, indicating input cost inflation remains elevated despite some easing.
-
The Inventories Index returned to expansion at 53.4 (+3.9 pts), while the Inventory Sentiment Index stayed in “too high” territory at 54.8 (-0.7 pts), suggesting firms are rebuilding or normalizing stock levels even as many still see inventories above business needs.
-
The Backlog of Orders Index improved to 49.1 (+8.3 pts) but stayed in contraction for a ninth month, recording its largest monthly increase since June 2022 and moving 3.8 pts above its 12-month average, pointing to a slower rate of backlog depletion.
-
New Export Orders (48.7, +0.9 pts) and Imports (48.9, +5.2 pts) both remained in contraction but improved from October, with comments highlighting mixed foreign demand, tariff-related headwinds, and some reshoring toward USMCA suppliers.
-
ISM noted that a Services PMI above 48.6 historically corresponds to overall GDP growth; November’s 52.6 reading implies roughly 1.3% annualized real GDP growth and marks the 66th consecutive month of overall US economic expansion, with 12 services industries reporting growth and 5 reporting contraction.
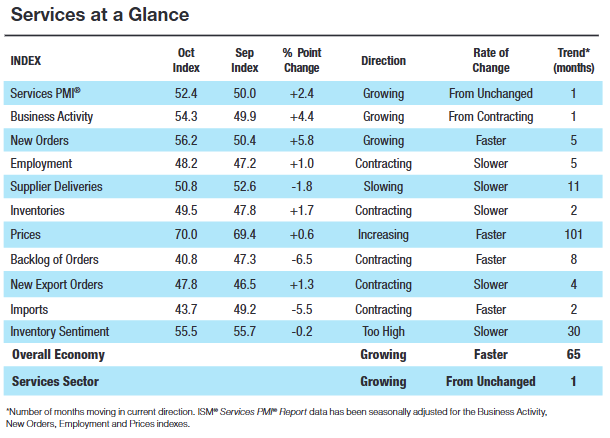
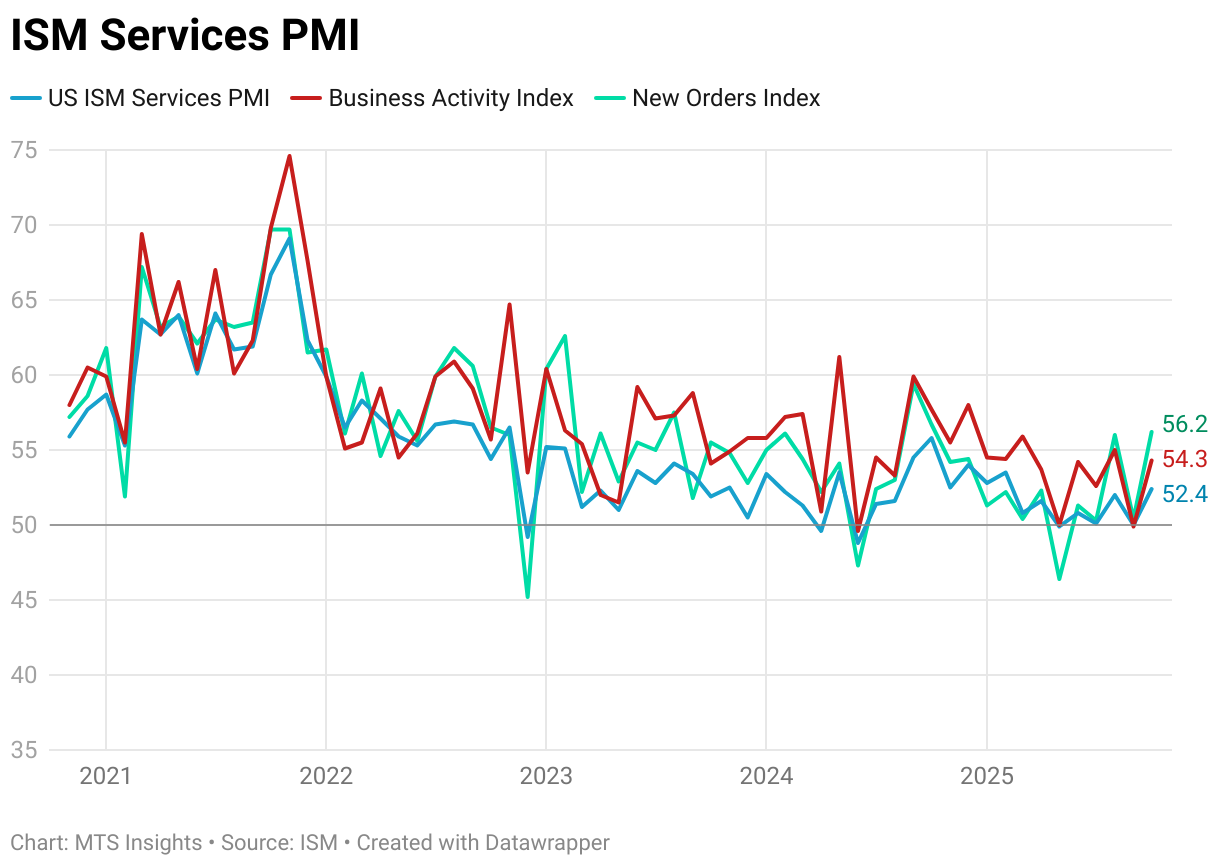
The ISM Services PMI rose +2.4 pts to 52.4 in October 2025 (from 50.0 in September), marking a return to expansion and signaling renewed growth momentum in the services sector.
-
Business Activity rebounded to 54.3 (+4.4 pts), indicating stronger output after briefly contracting in September.
-
New Orders surged to 56.2 (+5.8 pts), the fastest pace since October 2024, supported by improving demand and new client wins.
-
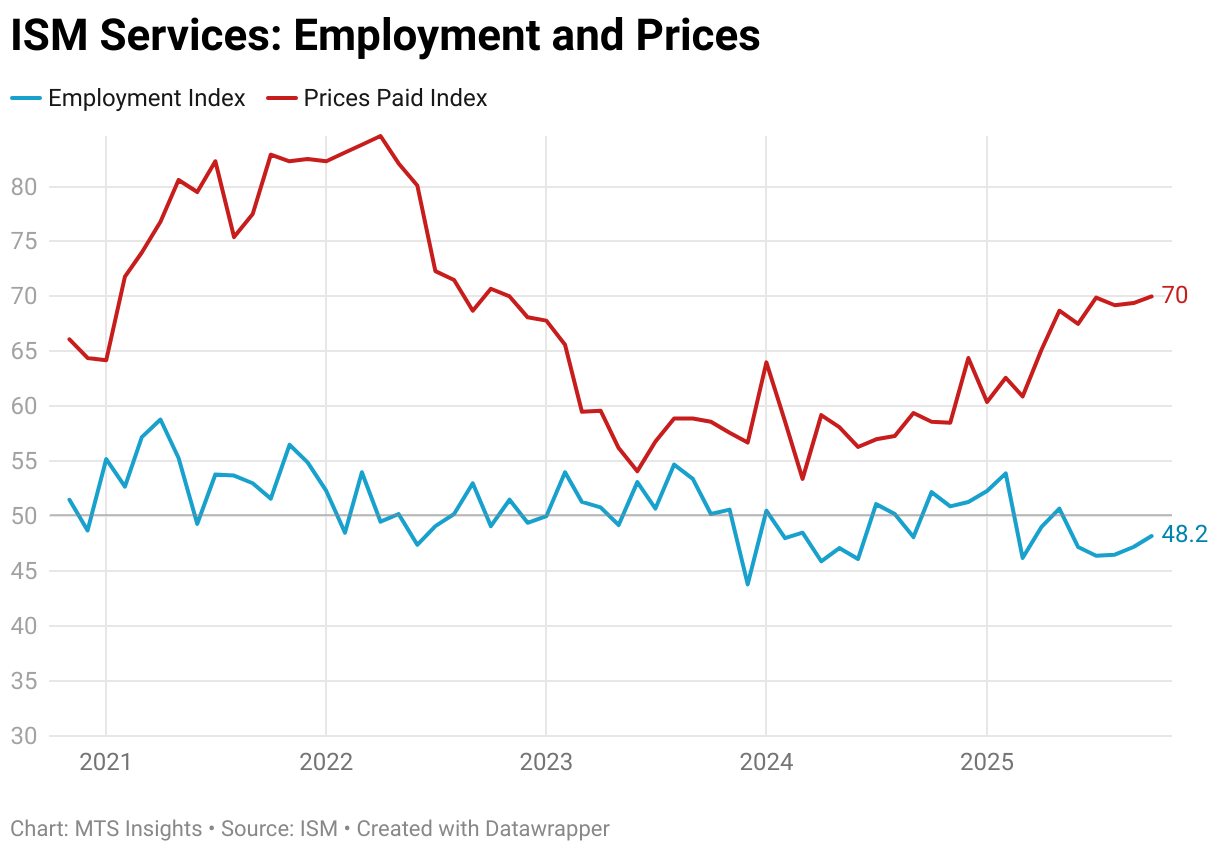
Employment remained in contraction at 48.2 (+1.0 pt), marking the fifth straight month of decline, though the pace of job losses slowed.
-
Supplier Deliveries eased to 50.8 (-1.8 pts), showing slower delivery performance for an 11th consecutive month as demand remained steady.
-
Prices Paid climbed to 70.0 (+0.6 pts), reaching the highest since October 2022 and extending the streak above 60 for 11 straight months.
-
Inventories stayed in contraction at 49.5 (+1.7 pts), while Inventory Sentiment remained elevated at 55.5, indicating stock levels still viewed as too high.
-
Backlogs fell sharply to 40.8 (-6.5 pts), the weakest since mid-2009, suggesting firms are comfortably meeting new orders.
-
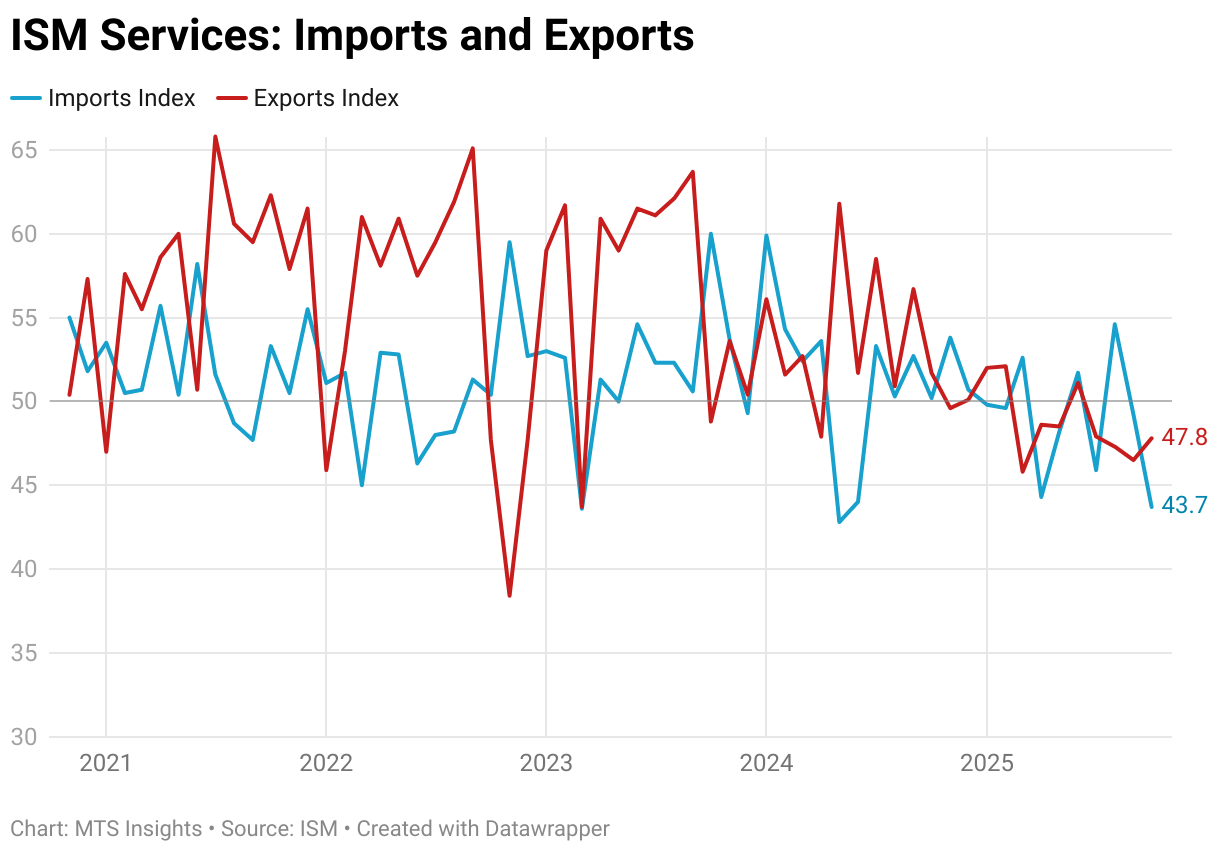
New Export Orders improved modestly to 47.8 (+1.3 pts) but remained in contraction, while Imports dropped further to 43.7 (-5.5 pts), reflecting reduced overseas sourcing.
-
ISM noted that October’s PMI corresponds to roughly 1.2% annualized GDP growth, with stable demand but continued caution in hiring and order backlogs.
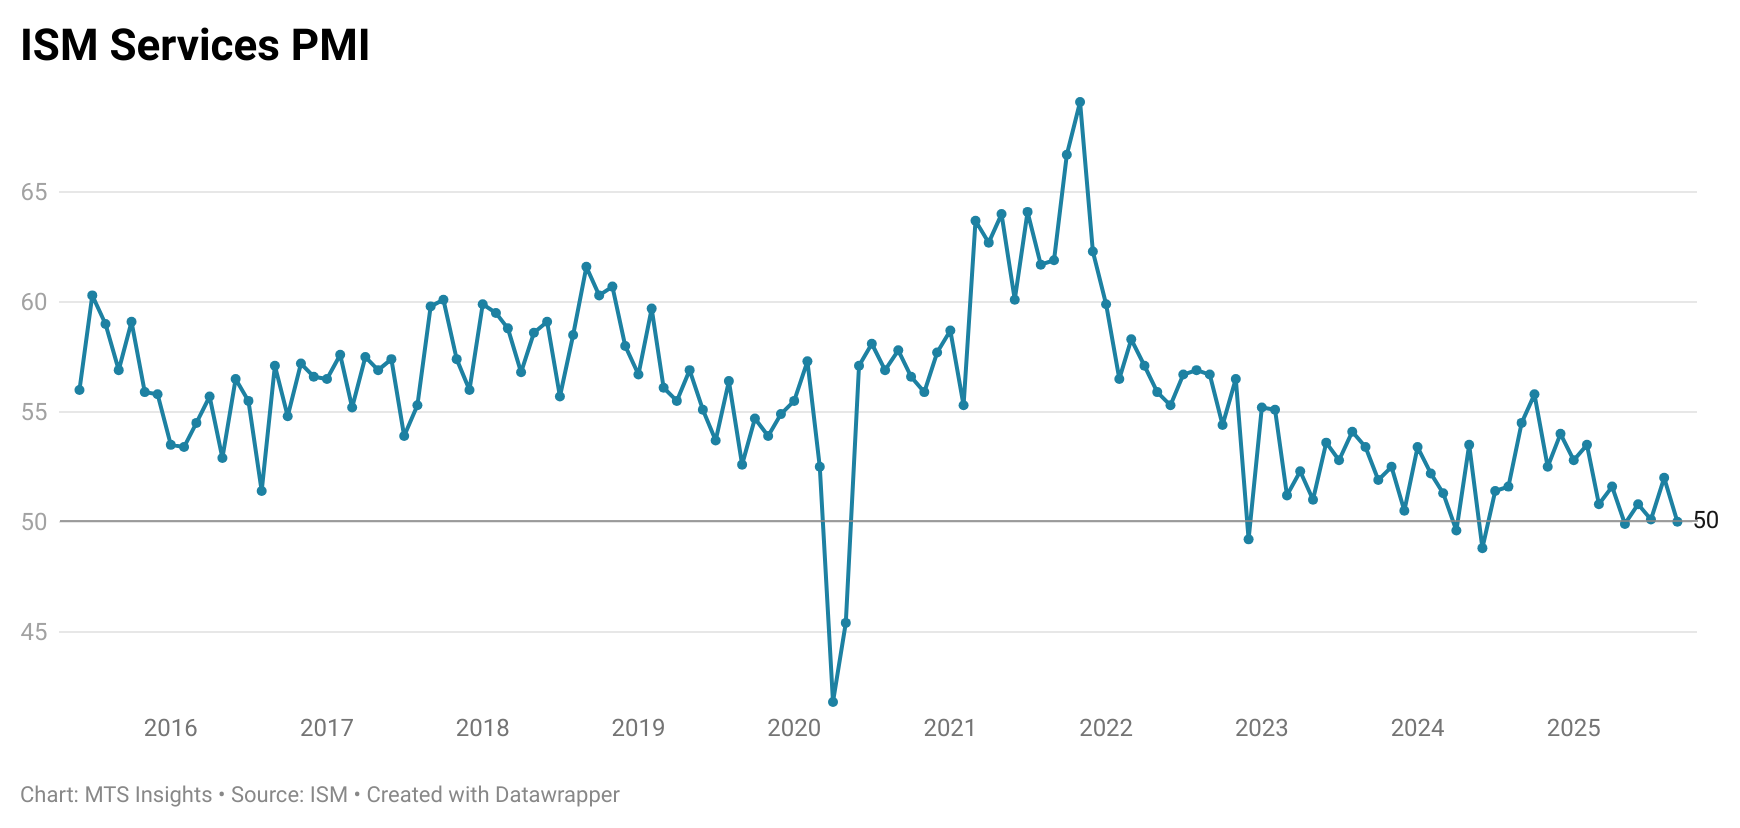
The ISM Services PMI fell to 50.0 in September (from 52.0 in August), the first breakeven reading since January 2010, signaling stagnation in the services sector after modest summer growth.
-
The Business Activity Index dropped -5.1 pts to 49.9, contracting for the first time since May 2020 as demand weakened.
-
New Orders slowed sharply, down -5.6 pts to 50.4, barely holding in expansion after strong August growth.
-
Employment remained in contraction at 47.2 (+0.7 pts), marking the fourth straight monthly decline and fifth in the past six months.
-
Supplier Deliveries rose +2.3 pts to 52.6, indicating slower deliveries for a 10th straight month, a sign of lingering supply-side challenges.
-
The Prices Index edged up to 69.4 (+0.2 pts), extending its streak above 60 to ten months and underscoring persistent cost pressures.
-
Inventories slipped into contraction at 47.8 (-5.4 pts), the lowest since January, while Inventory Sentiment rose to 55.7, reflecting continued perceptions of excess stock.
-
Backlogs improved to 47.3 (+6.9 pts) but remained in contraction for a seventh straight month, suggesting limited pipeline strength.
-
New Export Orders fell further to 46.5 (-0.8 pts), the third consecutive monthly decline, pointing to ongoing weakness in overseas demand.
-
Imports dropped back into contraction at 49.2 (-5.4 pts), after briefly expanding in August.