ICE First Look at Mortgage Performance: May 2026
Key takeaways:
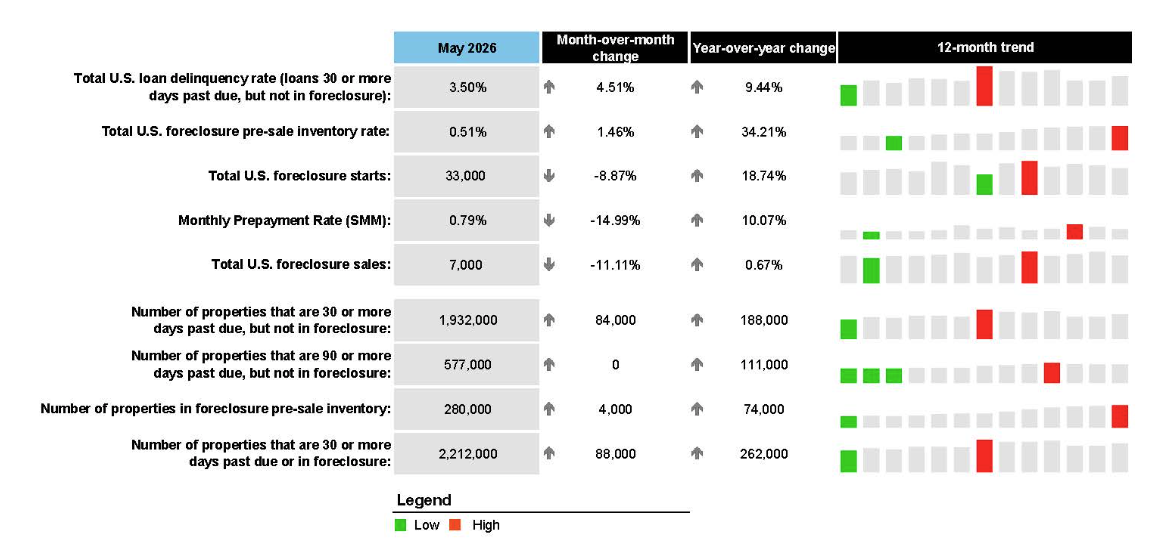
- The overall delinquency rate rose in May: The national delinquency rate rose 15 basis points (bps) to 3.50% due to a calendar anomaly. Overall delinquencies rose 4.5% month over month, which is in line with historical Sunday month-end patterns.
- Late-stage delinquencies improved to a five-month low: While serious delinquencies (90-plus days past due, but not in foreclosure) held steady from April and have improved seasonally from a five-month low, they are up 111,000 year over year — the largest annual increase since 2020.
- Foreclosure starts and inventory rose: Foreclosure starts fell 9% from April but remain 19% above year-ago levels. Active foreclosure inventory reached 280,000 loans, up 34% annually and the highest level in six years, though the foreclosure rate remains below pre-pandemic levels.
- Late-stage non-current loans rose: The number of loans that are seriously delinquent or in active foreclosure increased by 185,000 from a year ago, marking the largest year-over-year increase since the pandemic-era unemployment spike in 2020.
- Cure activity softened: Loans curing from serious delinquency declined 6% month over month in May, a decrease consistent with both typical seasonal patterns and the same month-end calendar effects that influenced delinquency counts. Cure volumes remain below late 2025 levels, with FHA cures continuing to lag broader market performance.
- Prepayment speeds cooled on higher rates: Single-month mortality (SMM), a measure of pre-payment speed, fell 15% from April’s 0.93% to 0.79% — a four-month low — as mortgage rates rose. May’s SMM remained 8 bps above year-ago levels.