

Bank of Canada Monetary Policy Decision: June 2026
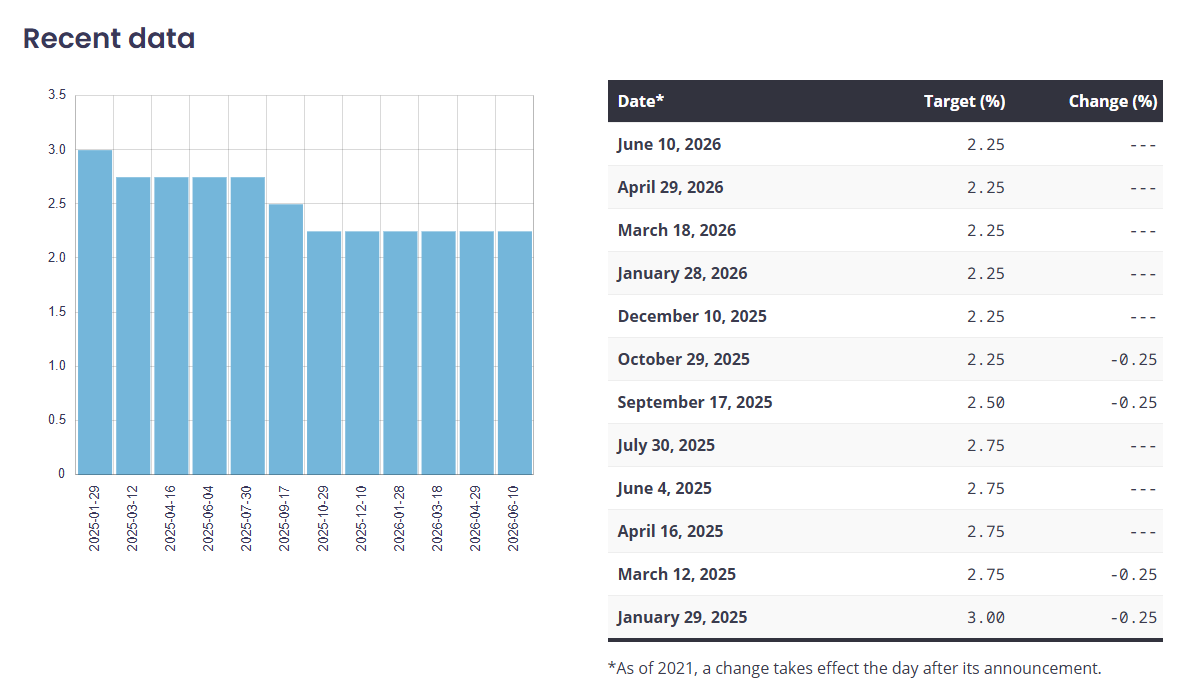
The Bank of Canada held its policy rate at 2.25% while CPI inflation rose to 2.8% YoY in April and GDP declined -0.1% QoQ in Q1 2026, reflecting weak domestic growth alongside energy-driven inflation pressures.
- The overnight rate was held at 2.25% (Bank Rate 2.5%, deposit rate 2.20%), indicating a continued pause in policy amid elevated uncertainty from geopolitical and trade developments.
- Canadian GDP declined -0.1% QoQ in Q1, coming in weaker than expected, with consumer spending rising +1.4% but offset by declines in government spending, housing activity, and weak business investment.
- Trade dynamics were negative for growth, with exports falling and imports rising strongly due to inventory rebuilding, indicating external and inventory-related drag on GDP.
- Labor market conditions remained soft, with employment little changed YTD and the unemployment rate fluctuating in the 6.5%–7.0% range (6.6% latest), pointing to subdued hiring conditions.
- CPI inflation increased to +2.8% YoY in April, driven primarily by higher energy prices and base effects from the removal of the consumer carbon tax, indicating a rebound in headline inflation.
- Core inflation measures declined to around 2%, and the share of CPI components above 3% remained near historical averages, suggesting limited broad-based inflation pressures beyond energy.
- Near-term inflation is expected to hover around ~3% before easing toward 2%, assuming oil prices moderate, indicating a temporary energy-driven inflation impulse.
- Financial conditions have loosened since April, with stronger equity markets, volatile bond yields, and a weaker Canadian dollar, reflecting shifting market dynamics despite economic softness.