


Weekly Petroleum Status Report: Week of February 6th
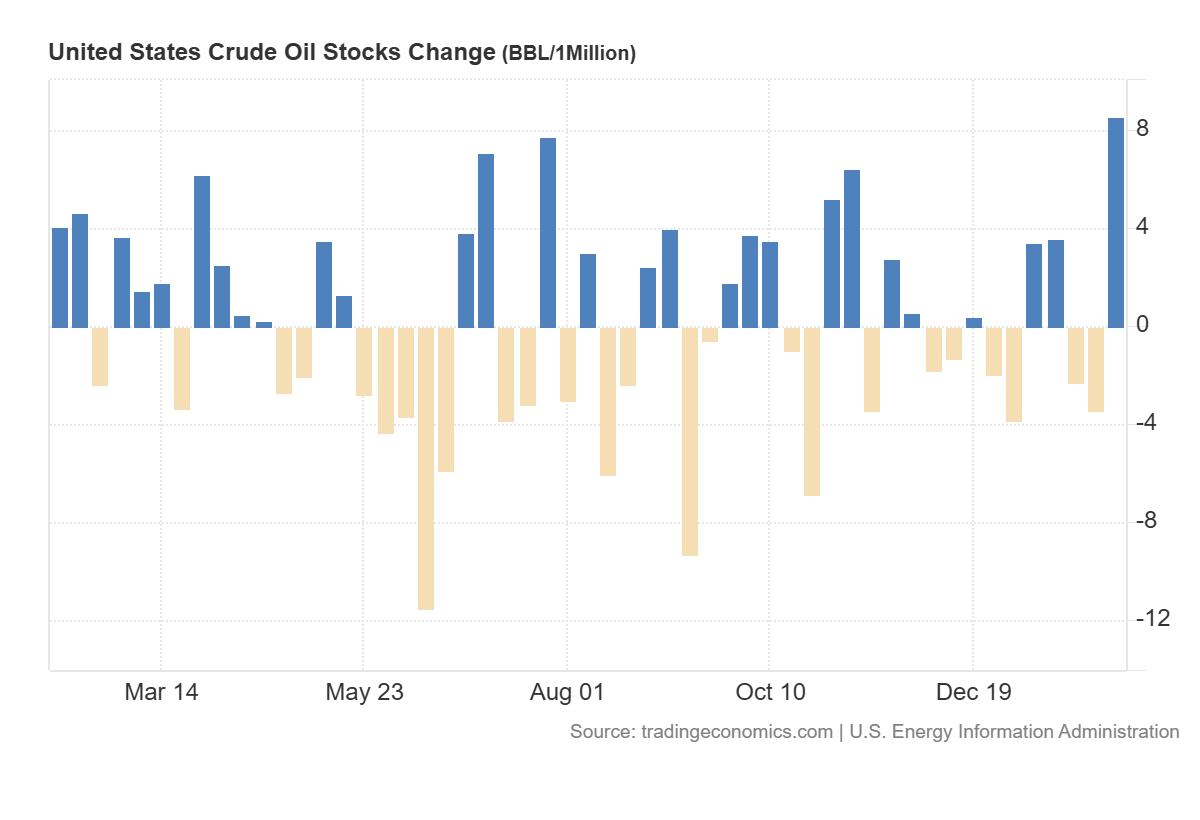
U.S. commercial crude inventories rose +8.5M (vs +0.8M) bbl WoW to 428.8M bbl in the week ending Feb. 6, 2026, while refined product stocks were mixed and demand trends diverged YoY.
-
U.S. crude oil refinery inputs averaged 16.0M bpd (-29k bpd WoW), with utilization at 89.4%, indicating slightly softer refinery runs compared with the prior week.
-
Gasoline production increased to 9.1M bpd, and distillate fuel production rose +45k bpd to 4.9M bpd, pointing to firmer refined product output despite lower utilization.
-
Crude oil imports rose +604k bpd WoW to 6.8M bpd; however, the four-week average of 6.3M bpd was -5.0% YoY, showing lower import volumes relative to last year.
-
Commercial crude inventories (ex-SPR) increased +8.5M bbl WoW to 428.8M bbl and remain about 3% below the five-year average, suggesting stocks are still modestly tight versus seasonal norms.
-
Total motor gasoline inventories rose +1.2M bbl WoW and are about 4% above the five-year average; finished gasoline declined while blending components increased, reflecting composition shifts within inventories.
-
Distillate fuel inventories fell -2.7M bbl WoW and sit about 4% below the five-year average, indicating continued drawdowns in middle distillate stocks.
-
Propane/propylene inventories decreased -5.4M bbl WoW but remain roughly 36% above the five-year average, keeping inventories elevated relative to historical levels.
-
Total products supplied averaged 20.8M bpd over the past four weeks (+2.4% YoY), with gasoline demand -0.7% YoY, distillate -3.2% YoY, and jet fuel -2.3% YoY, showing overall demand growth driven by categories outside the major fuels.