


Weekly Petroleum Status Report: Week of January 9th
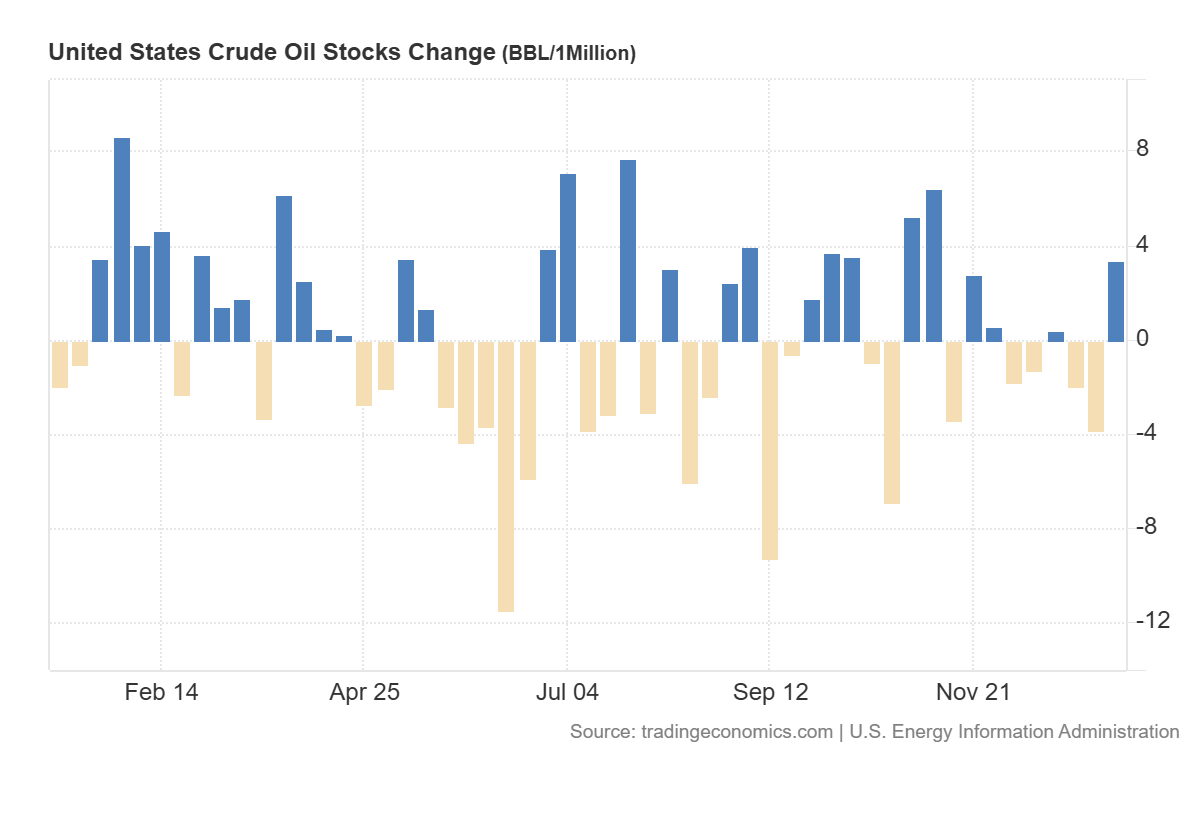
U.S. commercial crude oil inventories rose +3.4M bbl (vs -2.2M bbl) WoW to 422.4M bbl in the week ending Jan. 9, 2026, while refined product inventories were mixed.
-
U.S. crude oil refinery inputs averaged 17.0M bpd (+48k bpd WoW), with utilization rising to 95.3%, indicating slightly higher refinery runs week over week.
-
Gasoline production increased to 9.0M bpd, while distillate fuel production slipped -18k bpd WoW to 5.3M bpd, showing marginally weaker distillate output.
-
U.S. crude oil imports averaged 7.1M bpd (+752k bpd WoW), though the four-week average of 6.1M bpd was down -5.7% YoY, indicating lower import volumes versus last year despite the weekly jump.
-
Commercial crude inventories (ex-SPR) increased +3.4M bbl WoW to 422.4M bbl and remained about 3% below the five-year seasonal average, suggesting crude stocks are still relatively tight historically.
-
Total motor gasoline inventories surged +9.0M bbl WoW and moved to about 4% above the five-year average; finished gasoline inventories fell while blending components rose, indicating the build was concentrated in components.
-
Distillate fuel inventories edged slightly lower WoW and stood about 4% below the five-year average, implying distillate supply remains somewhat tighter than normal despite stability overall.
-
Propane/propylene inventories declined -2.4M bbl WoW but remained about 33% above the five-year average, highlighting continued oversupply relative to seasonal norms.
-
Total commercial petroleum inventories increased +6.2M bbl WoW, as large gasoline builds more than offset declines in other product categories.
-
Over the last four weeks, total products supplied averaged 20.0M bpd (-1.1% YoY); gasoline demand was roughly flat YoY at 8.5M bpd, while distillate demand rose +2.2% YoY and jet fuel demand increased +4.2% YoY, showing stronger usage trends outside gasoline.