

Kansas City Fed Manufacturing Survey: November 2025
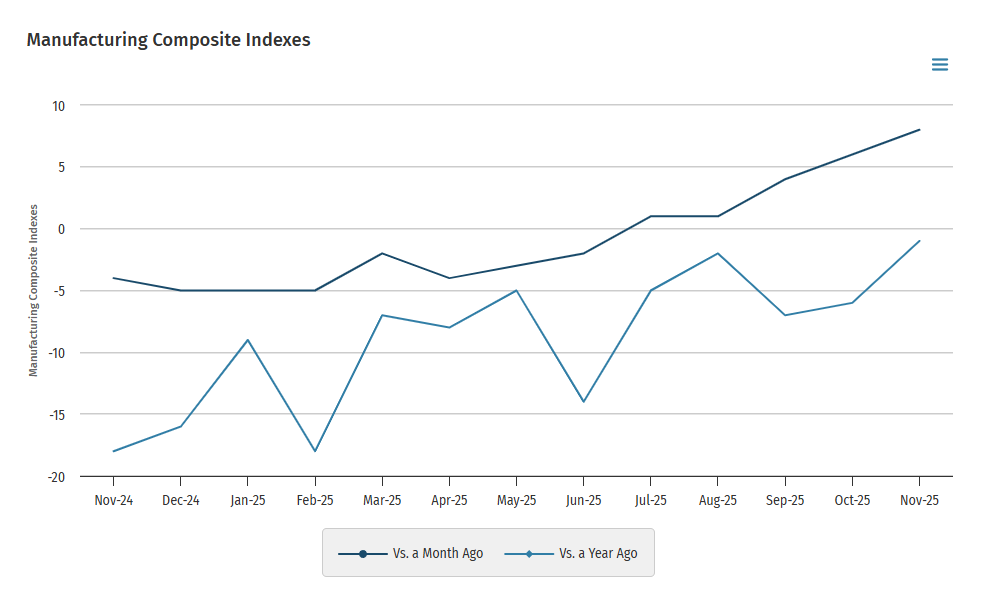
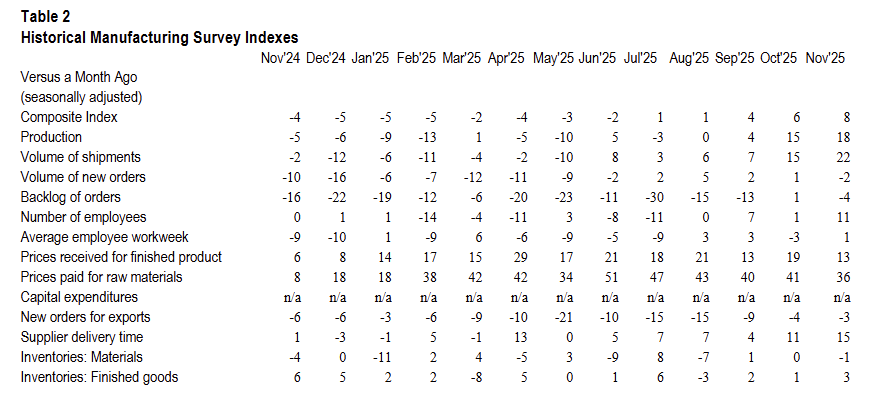
The Tenth District Manufacturing Composite Index rose to +8 in November (from +6 in October), marking a third straight month of strengthening factory activity across both durable and nondurable industries.
-
Production increased to +18 (Oct: +15), showing a stronger pickup in output, led by machinery, furniture, food, and printing manufacturing.
-
Shipments rose to +12 (Oct: +4), indicating firmer movement of finished goods compared with last month.
-
New orders held at +2 (Oct: +1), suggesting modest demand growth even as backlogs remained weak at -2 (Oct: -1).
-
Employment improved to +7 (Oct: +1), while the average employee workweek ticked up to +1 (Oct: -3), pointing to better labor utilization.
-
Prices received eased to +14 (Oct: +19) and prices paid softened to +34 (Oct: +37), showing slightly slower cost and selling-price pressures.
-
Inventories of materials declined to -1 (Oct: +1), while finished goods inventories increased to +3 (Oct: +2), reflecting mixed stock levels across inputs and outputs.
-
The future composite index dipped to +9 (Oct: +14), though firms’ expectations for future new orders (+6) and future employment (+11) both improved, keeping the near-term outlook positive.