


Weekly Petroleum Status Report: Week of November 7th
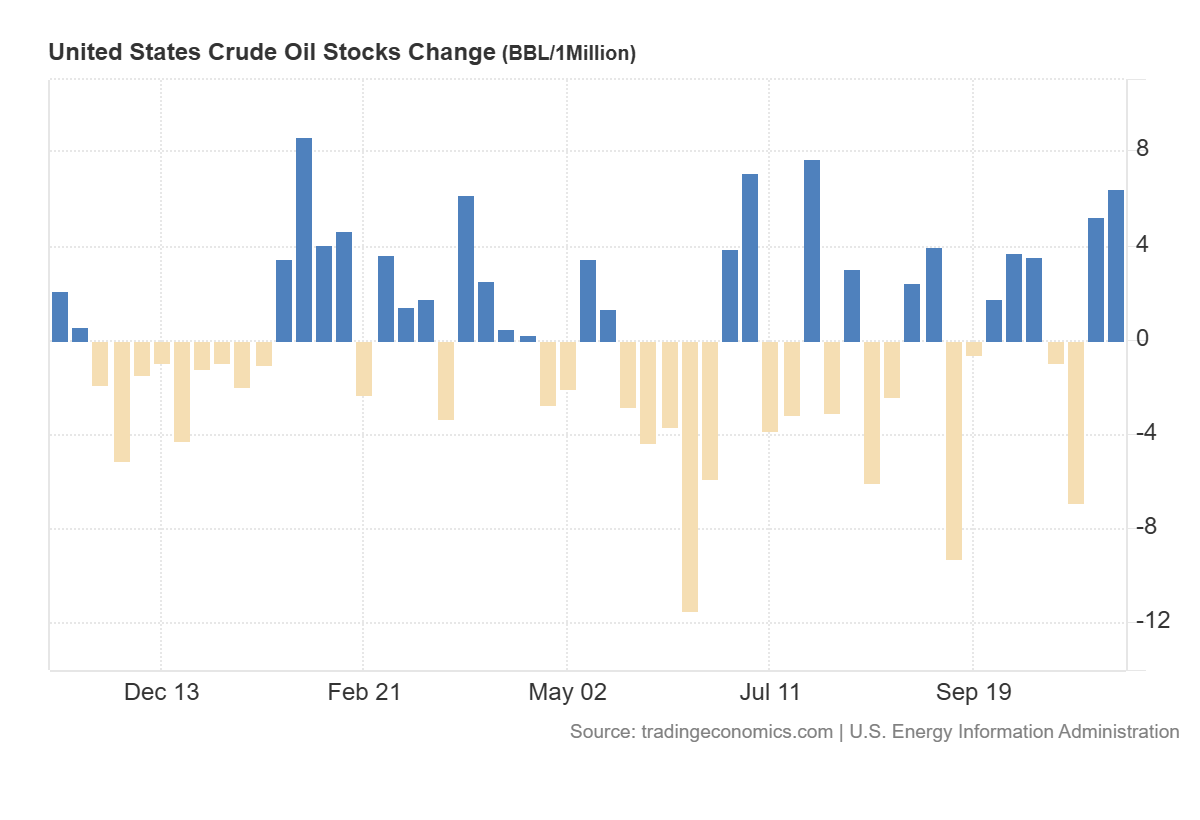
U.S. commercial crude oil inventories rose +6.4M bbl (vs +1.0M bbl) WoW to 427.6M bbl in the week ending November 7, 2025, about 4% below the five-year average, marking a sizable weekly build alongside stronger refinery runs.
-
Refinery inputs increased +717k bpd WoW to 16.0M bpd, with utilization at 89.4%, showing a notable pickup in processing activity.
-
Gasoline production averaged 9.9M bpd and distillate production averaged 5.0M bpd (+319k bpd WoW), indicating broadly stronger output across major refined products.
-
Crude imports fell -703k bpd WoW to 5.2M bpd, while the four-week average of 5.5M bpd was -12.1% YoY, highlighting weaker import demand versus last year.
-
Motor gasoline inventories declined -0.9M bbl and remained ~4% below their five-year norm; finished gasoline stocks rose but blending components fell.
-
Distillate inventories dropped -0.6M bbl and continued to sit ~8% below seasonal averages, pointing to persistent tightness in middle distillates.
-
Propane/propylene inventories slipped -0.7M bbl but stayed 16% above the five-year average, indicating ample supply despite the weekly draw.
-
Total commercial petroleum inventories increased +2.5M bbl as crude builds outweighed product declines.
-
Total products supplied averaged 20.6M bpd over the past four weeks (-0.9% YoY), with gasoline (-2.6% YoY) and distillate (-2.3% YoY) demand lower, while jet fuel usage rose +3.9% YoY.