ICE First Look at Mortgage Performance: September 2025
Key takeaways from this month’s findings include:
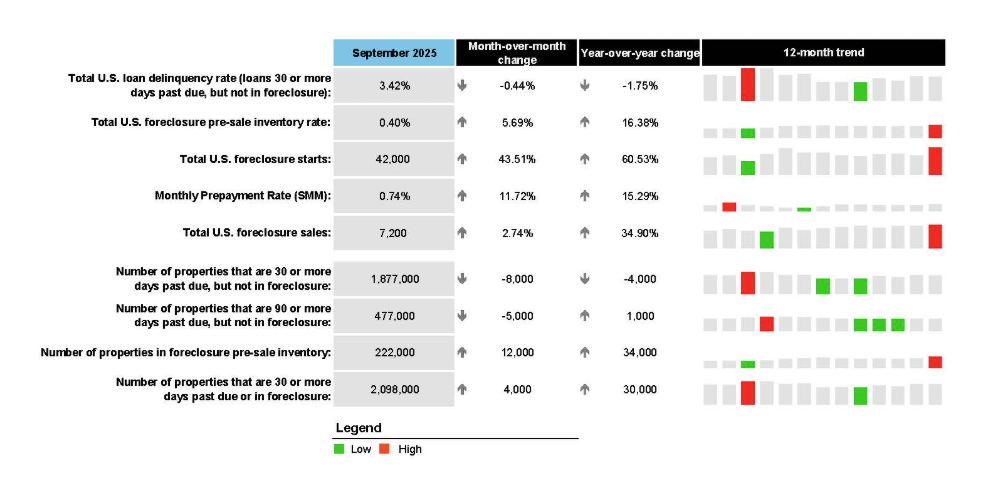
- Delinquencies remain well below pre-pandemic norms: The national delinquency rate fell by 2 basis points (bps) in September to 3.42%, down 6 bps from the same time last year and 58 bps below its September 2019 pre-pandemic level.
- Strength across delinquency bands in September: Both early-stage (30-day) and late-stage (90+ day) delinquencies improved month-over-month, as the vast majority of borrowers remain current on their mortgage payments.
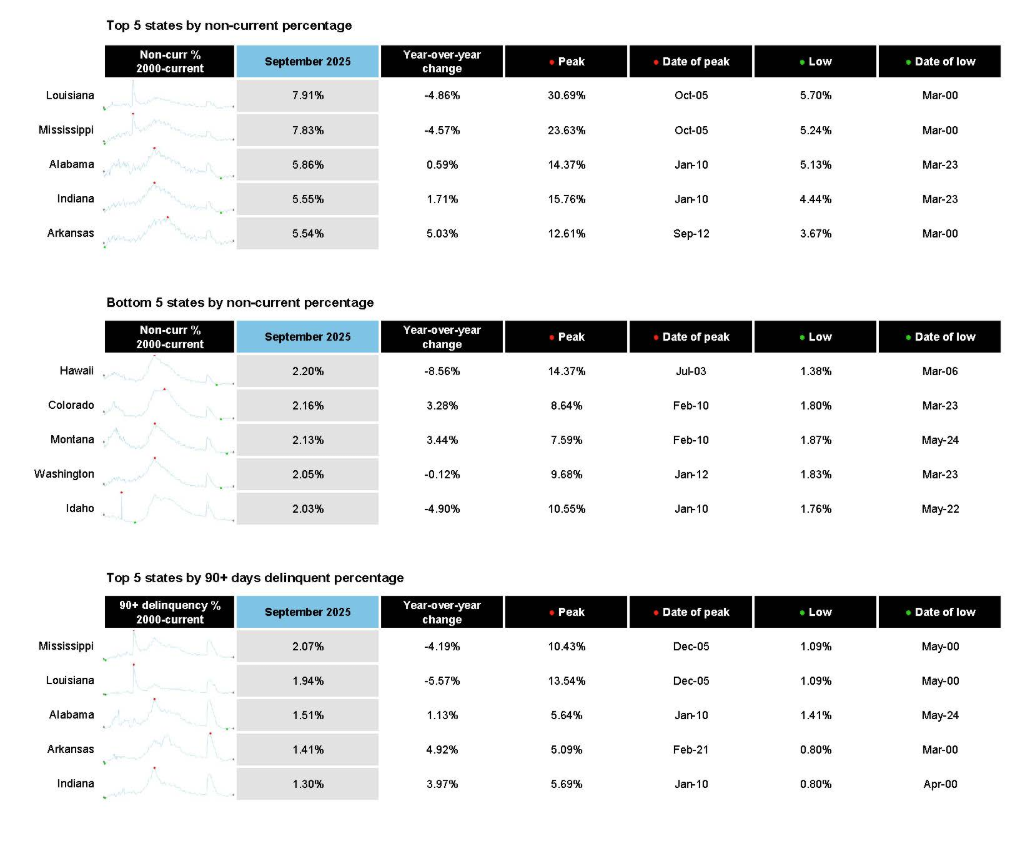
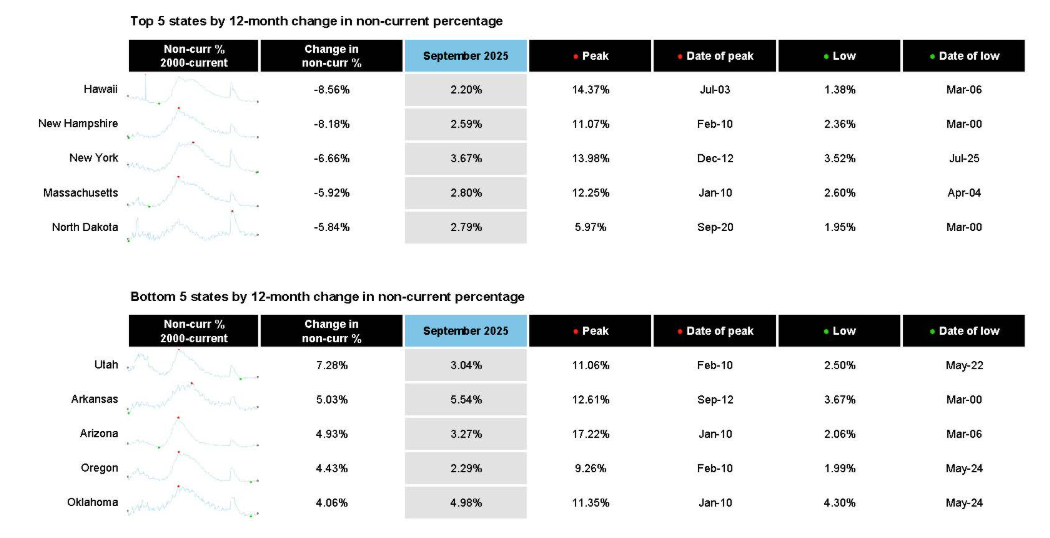
- Non-current rates improved for most investors: The non-current rate (delinquencies plus active foreclosures) declined year-over-year among GSE (-3 bps), VA (-4 bps) and portfolio-held loans (-17 bps). FHA loans were the notable exception, rising by 44 bps from last year’s levels.
- Foreclosure activity is returning to normal ranges: There were 103,000 foreclosure starts in Q3 2025, a 23% increase from the same period last year, but 18% below Q3 2019’s pre-pandemic levels.
- Improving efficiency in resolution: The number of loans in active foreclosure rose modestly year-over-year (18%), yet overall foreclosure volume remains historically low, with Q3 foreclosure sales (21,000) at roughly half of 2019 levels. FHA loans account for the majority of that rise, making up 38% of active foreclosures, roughly half of the annual rise in foreclosure starts and 80% of the rise in active foreclosures. The resumption of VA foreclosure activity following last year’s moratorium is largely responsible for the remainder.
- Prepayments are edging higher: Prepayments rose by 8 bps in September to a 0.74% single month mortality (SMM) rate, a 15% increase from the prior year, as interest rates began to ease in August.