


ECB Monetary Policy Decision: August 2026
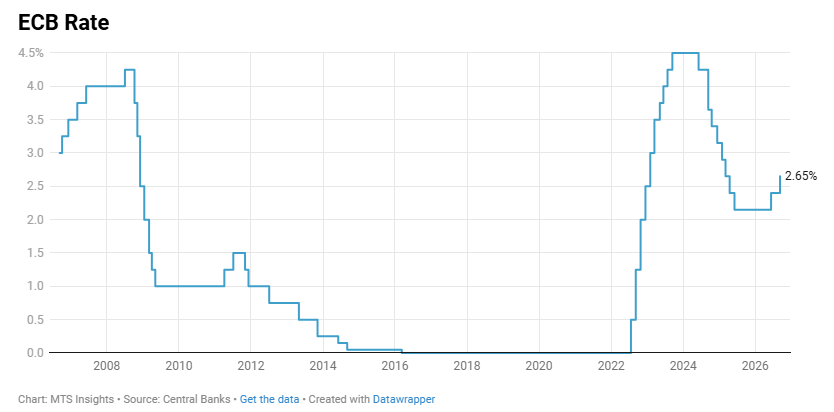
The ECB raised all three key policy rates by +25 bps, taking the deposit facility rate to 2.50%, the main refinancing rate to 2.65%, and the marginal lending rate to 2.90%, as persistent Middle East-related inflation pressures are expected to keep inflation well above target for an extended period.
-
The Governing Council raised the deposit facility rate to 2.50%, the main refinancing operations rate to 2.65%, and the marginal lending facility rate to 2.90%, all +25 bps, with the new rates taking effect on September 16, 2026.
-
Headline inflation is projected to average 3.0% in 2026, 2.5% in 2027, and 2.1% in 2028. The 2026 forecast was unchanged from June, while the 2027 and 2028 projections were revised higher, indicating a more persistent inflation profile.
-
Inflation excluding energy and food is projected at 2.5% in 2026, 2.6% in 2027, and 2.3% in 2028, remaining above the ECB's 2% target throughout the projection horizon.
-
Euro area GDP growth is projected at +0.9% in 2026, +1.4% in 2027, and +1.5% in 2028. The 2026 and 2027 forecasts were revised higher from June, mainly reflecting greater-than-expected resilience in the euro area economy.
-
The ECB said the outlook remains highly uncertain, with inflation risks tilted to the upside and economic growth risks to the downside, particularly given uncertainty around the intensity, duration, and indirect and second-round effects of the energy shock.
-
The Governing Council said the +25 bps increase reinforces its commitment to stabilizing inflation at its 2% medium-term target, while leaving future decisions dependent on incoming data, the inflation outlook, underlying inflation dynamics, and monetary policy transmission.
-
The ECB reiterated that decisions will be made meeting by meeting and that it is not pre-committing to a particular interest-rate path, preserving flexibility as the economic and inflation outlook evolves.
-
Balance sheet normalization is continuing, with the APP and PEPP portfolios declining at a measured and predictable pace as the Eurosystem no longer reinvests principal payments from maturing securities.